
Real estate has always been a core building block of a diversified portfolio, but for most retail investors in the EU, buying a physical property outright is out of reach — it takes tens of thousands of euros in cash, months of paperwork, and leaves you with one illiquid, undiversified asset. Two alternatives have grown popular instead: listed real estate companies (REITs) traded on the stock exchange, and real estate crowdfunding platforms that let you fund individual property loans or equity deals starting from as little as €50–€100. Here’s how the two compare in 2026, with real numbers.
REITs: liquid, but exposed to rate-driven price swings
European listed real estate had a rough stretch through mid-2026 as the ECB kept raising rates. The Xtrackers FTSE EPRA/NAREIT Developed Europe UCITS ETF, a common way to get broad exposure to the sector, was down 3.53% year-to-date and 1.02% over the trailing year as of 29 July 2026 (TER 0.33%), even though many of the underlying companies were still paying solid dividends.
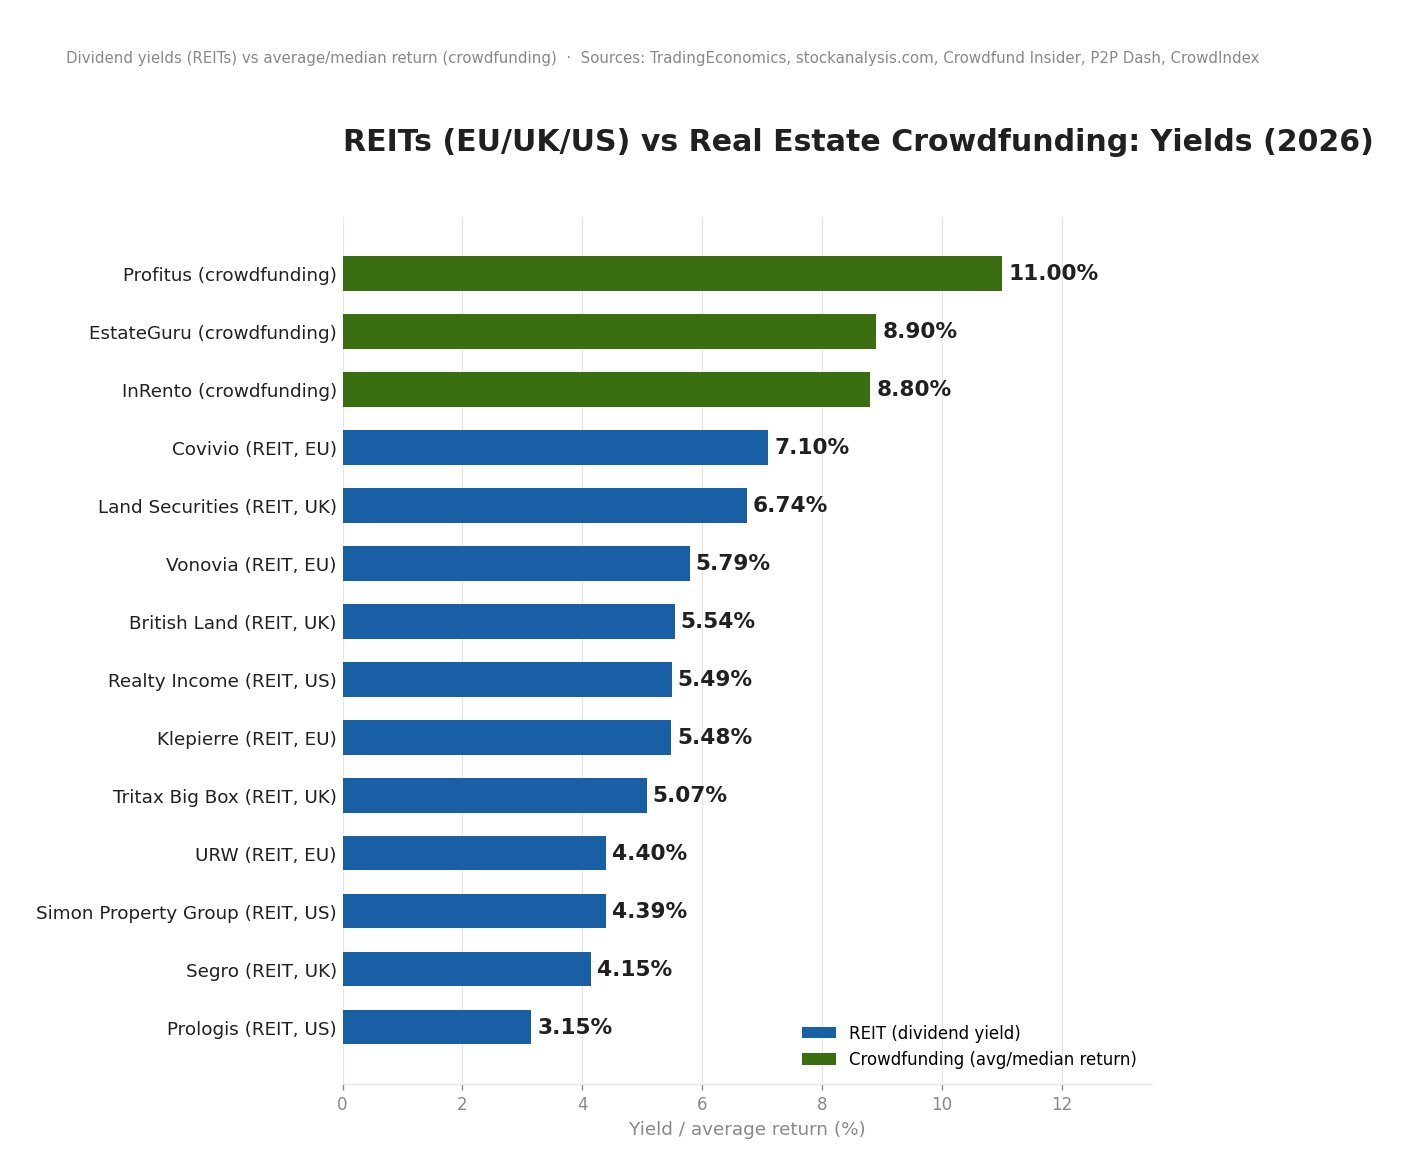
That’s the core trade-off with REITs: strong income, but share prices that move with interest-rate expectations. A sample of dividend yields from major REITs across Europe, the UK, and the US, as of mid-to-late 2026:
| Company | Region | Sector | Dividend yield | Source / period |
|---|---|---|---|---|
| Covivio | France (EU) | Diversified (offices, hotels, residential) | ~7.10% | stockanalysis.com, ex-div 15 Jul 2026 |
| Klepierre | France (EU) | Shopping centres | ~5.48% | TradingEconomics, FY2025 |
| Vonovia | Germany (EU) | Residential (Germany’s largest listed landlord) | ~5.79% | TradingEconomics, Q2 2026 |
| Unibail-Rodamco-Westfield | France/Netherlands (EU) | Shopping centres | ~4.40% | stockanalysis.com, May 2026 |
| Segro | UK | Logistics / industrial | ~4.15% | TradingEconomics, FY2025 |
| British Land | UK | Diversified (retail, offices, logistics) | ~5.54% | stockanalysis.com, 4 Jul 2026 |
| Land Securities | UK | Diversified (retail, offices, London mixed-use) | ~6.74% | stockanalysis.com, 18 Jun 2026 |
| Tritax Big Box REIT | UK | Logistics / big-box industrial | ~5.07% | stockanalysis.com, 23 Aug 2026 |
| Realty Income | US | Diversified net-lease (retail, industrial) | ~5.49% | stockanalysis.com, mid-Sep 2026 |
| Simon Property Group | US | Shopping malls / premium outlets | ~4.39% | stockanalysis.com, mid-Sep 2026 |
| Prologis | US | Logistics / industrial | ~3.15% | stockanalysis.com, mid-Sep 2026 |
Yields mostly in the 3–7% range are attractive on paper, but remember these are quoted on the current (often depressed) share price — and REIT share prices can fall faster than the underlying property values, especially in a rising-rate environment. European REITs have been most exposed to the ECB’s 16 September 2026 hike to 2.50%, while UK and US REITs move more with the Bank of England and the Fed — so a mix across regions also diversifies you across rate cycles, not just property markets.
Real estate crowdfunding: higher stated returns, but illiquid and platform-dependent
Crowdfunding platforms fund individual property loans (development, bridge, or rental-backed) or equity stakes, and let you invest from roughly €50–€100 per project. A single platform is never representative — returns and risk vary a lot — so here are three data points from established platforms, each with its own risk check:
- EstateGuru: investors earned €8.3 million in returns over the past year (€95m cumulative since inception), with €66m funded across 283 projects in that period. The average return on repaid loans was 8.9%, with a 97% on-time-or-repaid track record over three years (Crowdfund Insider, 27 Jan 2026). Its newer “EG Grow” product offers a fixed 7% annual rate.
- Profitus (Lithuania): a median net XIRR of roughly 10–12% across investor portfolios (P2P Dash, 14 Sept 2026; CrowdIndex, 1 May 2026, cites ~10%). It is licensed by the Bank of Lithuania under the EU’s crowdfunding (ECSP) framework, and we found no fraud, regulatory-warning, or insolvency reports as of September 2026. Two caveats worth flagging: its parent company reported negative shareholder equity in FY2024 (CrowdIndex), and its secondary market for exiting a loan early has been offline since May 2023.
- InRento (Lithuania, rental-income focused): a median net XIRR of 8.8% across tracked portfolios (9.4% over the trailing 12 months), per P2P Dash, 14 Sept 2026. It has held an EU-wide ECSP licence from the Bank of Lithuania since 10 Nov 2023, and we found no withdrawal freezes, regulatory warnings, or insolvency signals as of September 2026 — including after its 2022 merger with EvoEstate, which appears to have been a growth merger rather than a distressed bailout. One caveat: InRento’s rental-income projects generally carry no buyback guarantee, so credit and vacancy risk stays with the investor.
The catch: your money is typically locked for the stated loan or project term (often 12–36 months), secondary markets for exiting early are thin or non-existent on some platforms, and returns depend heavily on the platform correctly underwriting and, if needed, recovering defaulted loans — a risk that doesn’t show up in the headline yield.
Headline yields also vary enormously by platform, and so does platform risk. Some real estate crowdfunding platforms have run into serious trouble — frozen withdrawals, regulatory warnings, or worse — so a single platform’s reported or community-aggregated return figure should never be taken at face value. Before investing on any platform, check our list of platforms that have collapsed or run into serious financial difficulty, and treat it as the starting point for due diligence, not the end of it.
Side by side
| REITs | Real estate crowdfunding | Direct property | |
|---|---|---|---|
| Typical entry point | Price of 1 share (often €10–€100) | €50–€100 per project | Tens of thousands of euros+ |
| Liquidity | Daily, exchange-traded | Locked for loan/project term; limited secondary markets | Very low; months to sell |
| Return driver | Dividend + share price | Fixed or target interest rate | Rent + appreciation |
| Recent yield/return | ~4–7% dividend yield (2026) | ~5–9% (2025/2026, platform-dependent) | Highly local; net of costs often lower |
| Main risk | Share price volatility with rates | Platform/borrower default, illiquidity | Concentration, illiquidity, upkeep |
Where this leaves an investor
None of these is a straightforward “better” choice — they solve different problems. REITs give you daily liquidity and instant diversification — including across countries and rate cycles, since EU, UK, and US REITs don’t always move together — but expose you to stock-market-style price swings tied to interest rates. Crowdfunding platforms can offer higher headline yields and let you pick individual projects, but you’re taking on illiquidity and platform/credit risk in exchange, and that risk varies a lot by platform, as our own experience tracking failed and struggling P2P and crowdfunding platforms shows. Direct property still offers the most control (and potential leverage via a mortgage), but demands the most capital and the least flexibility.
For most retail investors, a mix — a broad REIT ETF for liquid core exposure, plus a modest, diversified allocation across a couple of established crowdfunding platforms — spreads the specific risks of each vehicle rather than betting everything on one.
Disclaimer: This article is for informational purposes only and does not constitute investment advice. Investing involves risk, including the possible loss of capital — past performance and stated yields are not guarantees of future results. Some figures cited (e.g. platform-aggregated return data) are third-party estimates rather than official statistics, as noted in the text. This article may contain affiliate links; if you sign up through them, we may earn a commission at no extra cost to you.