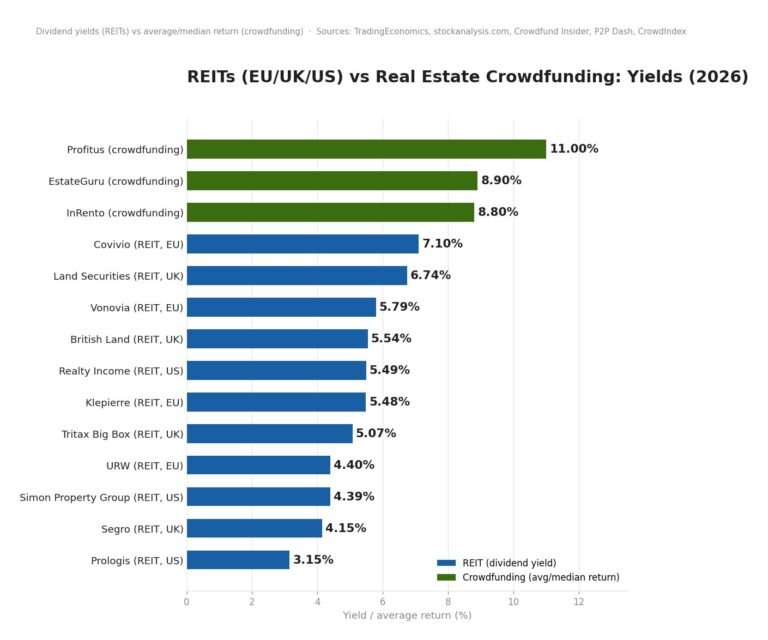
These three new InRento crowdfunding projects, launched in September 2026, give investors a way to spread a single decision across Latvia, Poland and Romania in one sitting. InRento — the Vilnius-based, Bank of Lithuania-regulated buy-to-let and built-to-let crowdfunding platform I’ve covered before in the REITs vs. real estate crowdfunding comparison — opened three new financing rounds in September 2026, one each in Latvia, Poland and Romania. All three are secured by a first-rank mortgage on the underlying property, which lets investors spread a single decision across three different markets rather than betting on one. Here’s what each project actually involves, with the numbers laid out side by side, based on InRento’s own project pages and September 2026 newsletter.
How these deals are structured
All three rounds follow the same mechanics, so it’s worth explaining once rather than three times. Each is a loan to a property developer, secured by a first-rank mortgage on the project’s assets (meaning InRento investors are first in line on that collateral if the developer defaults) plus a loan-to-value (LTV) ratio that caps how much is lent relative to the property’s appraised value — the lower the LTV, the bigger the equity buffer under the loan. Investors earn a fixed monthly interest rate plus a fixed 1.5% p.a. capital gain paid out at maturity, and the maximum loan duration on all three is 24 months. None of this eliminates risk — a mortgage and a conservative LTV reduce how much investors stand to lose if something goes wrong, they don’t guarantee the return or the timeline.
P10, Riga III (Latvia)
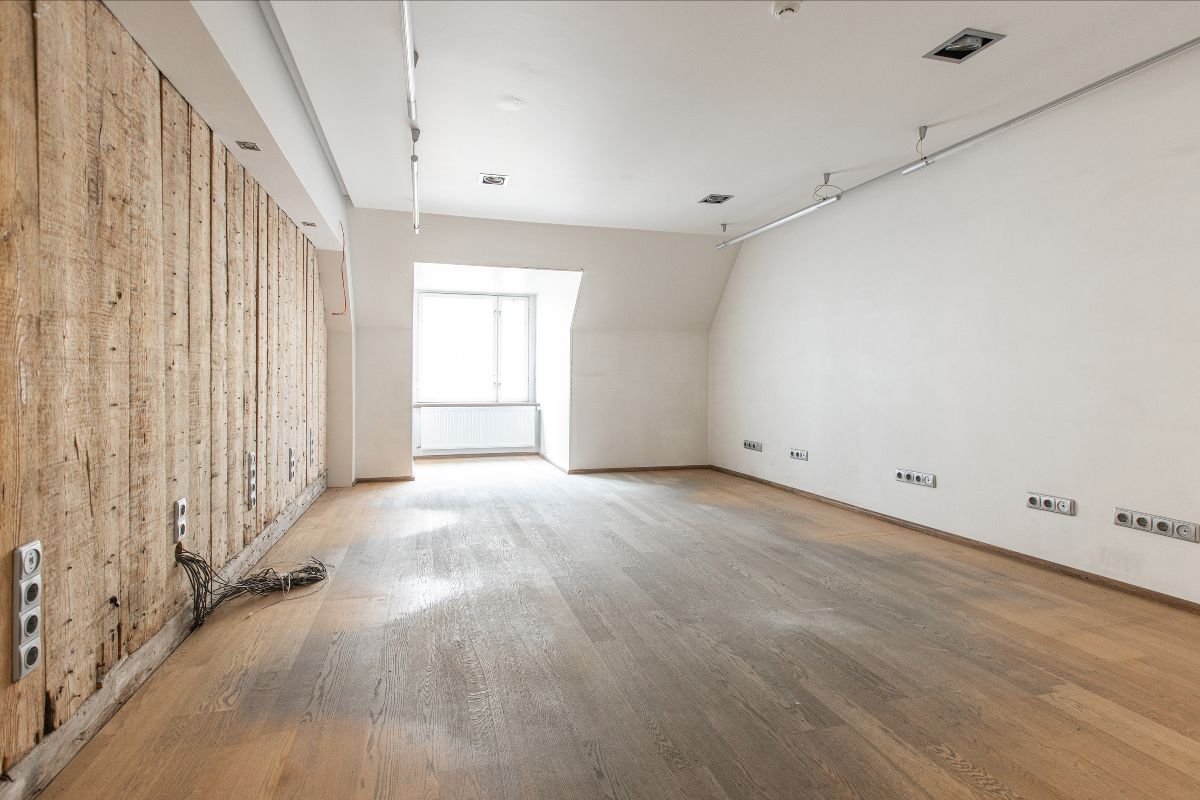
This is the third financing stage of a buy-to-let conversion in Riga’s Old Town: two administrative buildings being turned into a 26-room boutique hotel aimed at the city’s growing demand for centrally located short stays. Per InRento, the project owner expects around €160,000 in annual profit once the hotel is fully operational. Since the previous stage, the roof has been finished, ground-floor windows replaced and furniture purchased, with painting, bathroom work and carpet installation ongoing; the remaining windows are due in the coming weeks.
- Security: first-rank mortgage + surety agreement, LTV up to 70%, collateral value €1,043,200
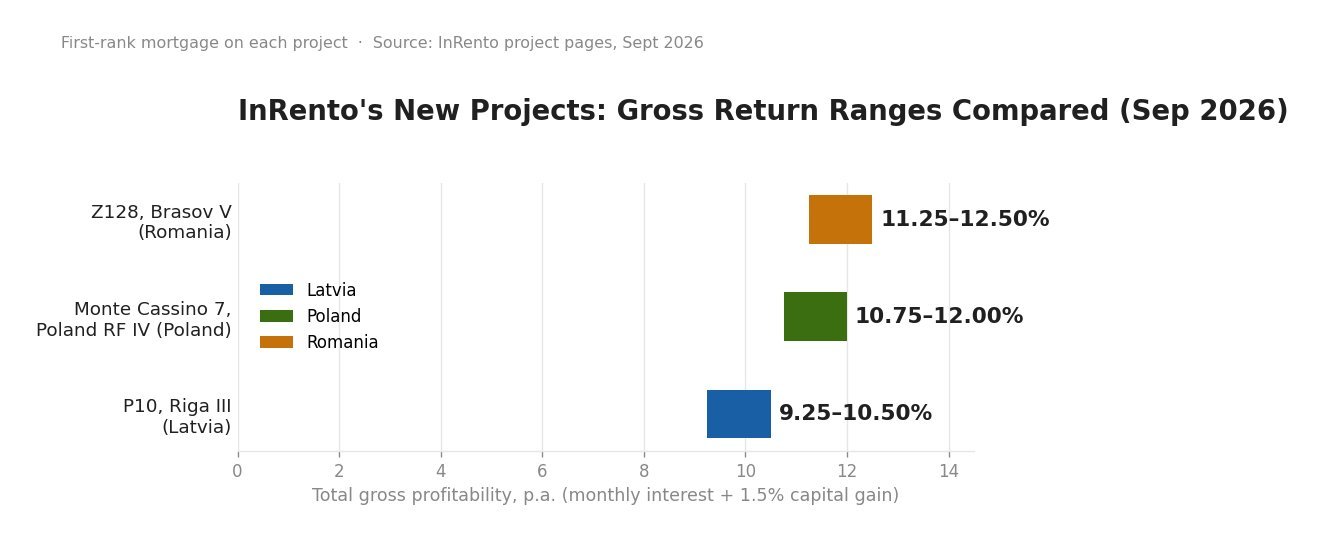
- Return: 7.75–9% p.a. monthly interest + 1.5% p.a. capital gain at maturity = 9.25–10.5% p.a. gross
- Max duration: 24 months
Monte Cassino 7, Poland RF IV (Poland)
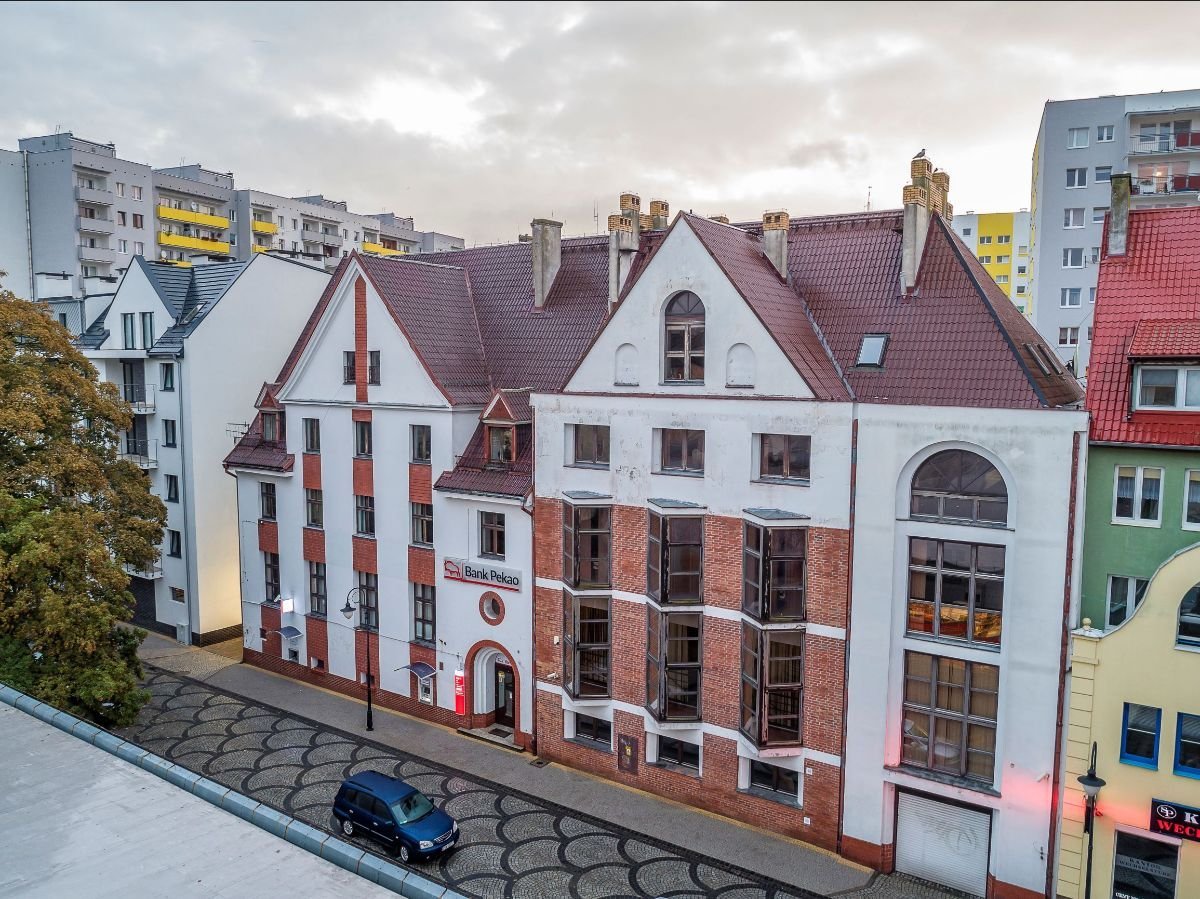
The fourth financing stage for a five-storey building (2,597.95 sq. m., on a 1,215 sq. m. plot) in Świnoujście, being converted into 25–40 sq. m. rental apartments with a gym, sauna and bike storage. Świnoujście itself sits directly on the Polish-German border — it adjoins the German seaside resort of Ahlbeck via a shared beach promenade — and has Poland’s largest and most modern ferry terminal, with connections to Denmark and Sweden. Per InRento, the property is a few hundred metres from the passenger terminal and around 1.6 km from the beach, with a supermarket, spa park, school and kindergarten nearby.
- Security: first-rank mortgage, LTV up to 49%, collateral value €4,539,517
- Return: 9.25–10.5% p.a. monthly interest + 1.5% p.a. capital gain at maturity = 10.75–12% p.a. gross
- Max duration: 24 months
Z128, Brasov V (Romania)
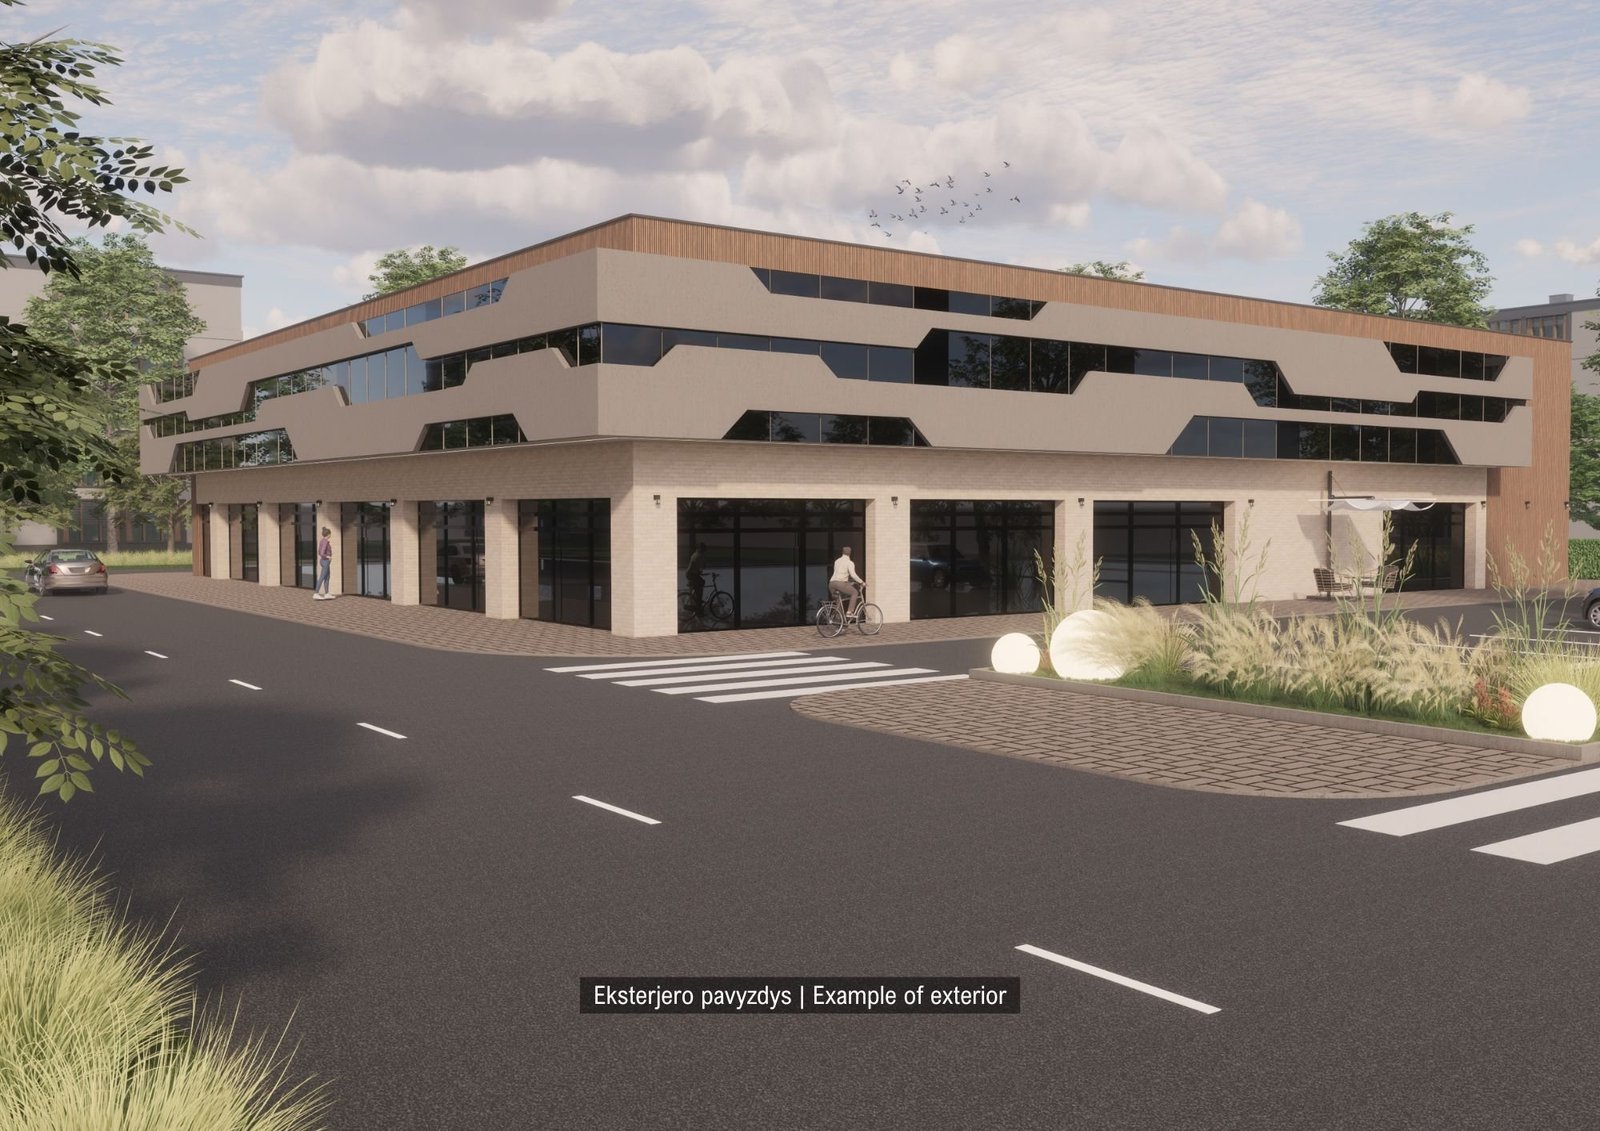
Rendering / example of exterior, not a live photo of current construction progress.
The fifth financing stage of a built-to-let mixed-use commercial complex in Brasov — Romania’s second most-visited city after Bucharest, with a city-proper population of roughly 237,600 and a metro-area population of about 372,000 as of the 2021 census. Since the previous stage, facade insulation has reached roughly 80%, interior plastering is largely finished, the ground-floor slab has been poured, and windows, doors and utility connections are being installed. Per InRento, long-term lease agreements are already signed with Supeco (a Carrefour Group brand) and 18Gym, expected to bring in €25,000 in monthly rental income once operational; because the deal is structured entirely in EUR, currency risk sits with the project owner rather than investors.
- Security: first-rank mortgage, LTV 64% (max. 70%), collateral value €1,686,000
- Return: 9.75–11% p.a. monthly interest + 1.5% p.a. capital gain at maturity = 11.25–12.5% p.a. gross
- Max duration: 24 months
InRento crowdfunding projects, side by side
| Project | Country | Type | LTV | Monthly interest | Capital gain (at maturity) | Total gross, p.a. | Max duration |
|---|---|---|---|---|---|---|---|
| P10, Riga III | Latvia | Buy-to-let | up to 70% | 7.75–9% | 1.5% | 9.25–10.5% | 24 months |
| Monte Cassino 7, RF IV | Poland | Buy-to-let | up to 49% | 9.25–10.5% | 1.5% | 10.75–12% | 24 months |
| Z128, Brasov V | Romania | Built-to-let | 64% (max. 70%) | 9.75–11% | 1.5% | 11.25–12.5% | 24 months |
Source: InRento project pages and investor newsletter, September 2026.
What the mortgage security does (and doesn’t) cover
The lower a project’s LTV, the more equity sits below the loan before an investor’s capital is at risk — which is why Monte Cassino 7’s 49% LTV looks more conservative on paper than Z128’s 64%, even though Z128 pays a higher headline return. A first-rank mortgage means InRento investors get paid from a sale of the collateral before other creditors, but it doesn’t guarantee a quick or full recovery if a developer defaults, and two of these three projects (Riga and Brasov) are still mid-construction, which carries its own completion and timeline risk on top of the usual credit risk. Putting money into a single project also concentrates risk in a way a diversified REIT or fund doesn’t — spreading an allocation across several projects, or across platforms and asset types the way we compared in the REITs vs. crowdfunding article, is the usual way to manage that.
For context: InRento reports a 0% formal default rate across its funded projects as of September 2026 (per its own statistics page, corroborated by independent reviews such as rethink-p2p.de and p2pempire.com), with 99% of completed projects repaid ahead of schedule. That’s worth taking with a bit of nuance, though — a small amount of interest was reported late as of August 2026, at least two Polish projects had late payments around the same time, and InRento’s mortgage-enforcement process hasn’t actually been tested in a real recovery, since nothing has needed it yet. There have also been investor complaints from 2022–2023, mostly tied to InRento’s merger with EvoEstate, about slow capital returns and communication — administrative friction rather than loan defaults, but worth knowing about.
If any of these three InRento crowdfunding projects fits what you’re looking for, you can review the full terms and browse InRento’s current projects here.
Disclaimer: This article is for informational purposes only and does not constitute investment advice. All figures above (returns, LTV, collateral values, construction progress, and lease terms) are as published by InRento in September 2026 and reflect the project owner’s own projections, not independently verified outcomes; timelines and returns are estimates and can change. All investing carries risk, including the possible loss of some or all of your money — diversify and invest responsibly. This reflects my personal opinion and is not financial advice; nothing here is guaranteed or risk-free. This article contains affiliate links; if you invest through them, I may earn a commission at no extra cost to you.