The Coca-Cola Company (NYSE: KO) will report third-quarter 2026 results on October 27, 2026, before the New York Stock Exchange opens, with a conference call at 8:30 a.m. Eastern. The company raised its full-year guidance in July. What matters for this report is what that guidance implies for the second half, because it points to a much slower pace than the first half. Below: the recent quarters, each compared with the same quarter a year earlier, the guidance, my calculation of what it implies, the dividend, and what to watch.
The recent quarters, each against the same quarter a year earlier
| Metric (change vs same quarter a year earlier) | Q3 2025 (the base for Q3 2026) | Q1 2026 | Q2 2026 |
|---|---|---|---|
| Net revenues | $12.5 billion, +5% | $12.5 billion, +12% | $13.4 billion, +7% |
| Organic revenues (non-GAAP) | +6% | +10% | +6% |
| Unit case volume | +1% | +3% | +5% |
| Comparable EPS (non-GAAP) | $0.82, +6% | $0.86, +18% | $0.97, +11% |
| Comparable operating margin (non-GAAP) | 31.9% (prior year 30.7%) | 34.5% (prior year 33.8%) | 35.6% (prior year 34.7%) |
Sources: Coca-Cola results releases of October 21, 2025, April 28, 2026 and July 28, 2026. Each growth rate and margin is against the same quarter of the previous year, so compare the columns only within themselves; quarterly margins differ with the seasons, which is why the third quarter should be judged against the third quarter of last year.
Full-year guidance: three updates, same metrics
| Full-year 2026 guidance | Feb 10, 2026 | Apr 28, 2026 | Jul 28, 2026 |
|---|---|---|---|
| Organic revenue growth (non-GAAP) | 4% to 5% | 4% to 5% | about 5% |
| Comparable EPS growth (non-GAAP, vs $3.00 in 2025) | 7% to 8% | 8% to 9% | 9% to 10% |
| Comparable currency neutral EPS growth, excluding acquisitions and divestitures | 5% to 6% | 6% to 7% | 7% to 8% |
| Free cash flow (non-GAAP) | not reviewed | about $12.2 billion | about $12.4 billion |
The July release also states an underlying effective tax rate of 19.9% (unchanged), a currency tailwind of about 3% and an acquisitions and divestitures headwind of about 1% for comparable EPS (both unchanged), and a currency tailwind of about 1% (previously 1% to 2%) with a headwind of 2% to 3% (previously about 4%) for comparable net revenues. In April the company noted that its guidance assumes the pending sale of Coca-Cola Beverages Africa closes in the second half of 2026, and that the tax rate excludes any impact of the ongoing U.S. IRS tax litigation. Sources: Coca-Cola releases of February 10, April 28 and July 28, 2026.
What the guidance implies for the second half (my calculation)
| Step | Comparable EPS |
|---|---|
| Full-year 2025 (Feb 10, 2026 release) | $3.00 |
| Full-year 2026 guidance: +9% to +10% | $3.27 to $3.30 |
| First half 2026 actual: Q1 $0.86 + Q2 $0.97 | $1.83 |
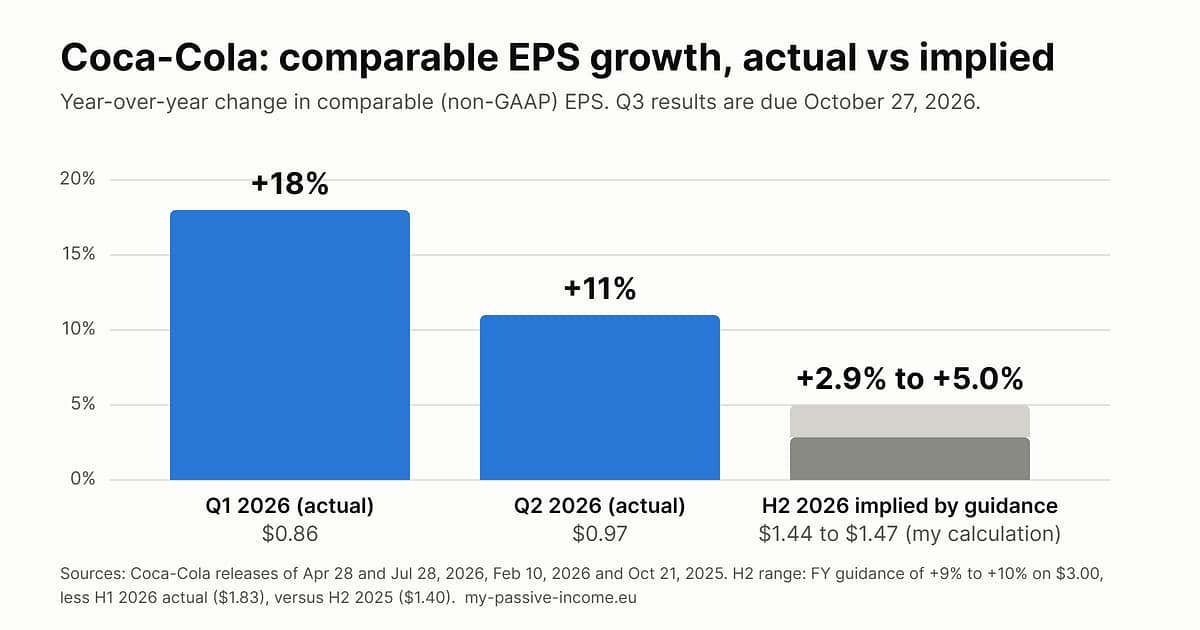
| Implied second half 2026 | $1.44 to $1.47 |
| Second half 2025 actual: Q3 $0.82 + Q4 $0.58 | $1.40 |
| Implied second-half growth (H2 2026 vs H2 2025) | +2.9% to +5.0% |
| For reference, first-half growth (H1 2026 $1.83 vs H1 2025 $1.60, which is $3.00 less $1.40) | +14.4% |
Every comparison here is a half-year against the same half-year. The guidance rates are rounded to whole percentages, and one percentage point on $3.00 is $0.03, so the true range is wider than the arithmetic shows. I did not see quarterly guidance in the releases I reviewed, so the split between Q3 and Q4 is not given. As an illustration only, not a forecast: if Q3 grew at the implied second-half pace, comparable EPS would be roughly $0.84 to $0.86 against $0.82 a year earlier.
A drop from about +14% growth in the first half to roughly +3% to +5% in the second can mean two things: the guidance leaves room to beat it, or there are second-half headwinds the company has not spelled out in the releases I read. The sale of Coca-Cola Beverages Africa assumed for the second half is one item to ask about; the call should show which reading is right.
What analysts expect, and the share price
This section uses third-party data, which is not from the company; each figure carries its source and time. Consensus is for the same quarter, compared with the same quarter a year earlier.
| Q3 metric | Consensus for Q3 2026 | Q3 2025 actual (company) | Change |
|---|---|---|---|
| Comparable EPS | $0.87 (Zacks, Oct 22, 8:15 a.m. EDT); $0.88, exactly $0.881 (MarketBeat, Oct 20) | $0.82 | +6.1% to +7.4% |
| Net revenues | $12.93 billion (Zacks, Oct 22); $12.92 billion (MarketBeat, Oct 20) | $12,455 million reported; $12,412 million comparable | +3.7% to +3.8% on reported; +4.1% to +4.2% on comparable (the consensus basis is not stated) |
If Q3 comes in at consensus, the full-year guidance leaves less for the fourth quarter. Using my calculation above, the implied second half of $1.44 to $1.47 less a third quarter of $0.87 to $0.88 means a fourth quarter of about $0.56 to $0.60, against $0.58 in Q4 2025: between roughly -3% and +3% growth, quarter against quarter. A Q3 result above consensus, or a guidance raise, would change that picture.
On October 22, 2026, at 1:11 p.m. Eastern, KO traded at $94.68 (intraday, not a closing price; source: 24/7 Wall St.). Against the July 28 full-year guidance, this gives (my calculation):
| Measure | Value |
|---|---|
| Share price (intraday, Oct 22, 2026, 1:11 p.m. ET) | $94.68 |
| 2026 comparable EPS guidance: $3.27 to $3.30 (+9% to +10% on $3.00) | price to guidance: 28.7x to 29.0x |
| Quarterly dividend of $0.53, $2.12 a year | yield 2.24% on the price above |
| Annual dividend as a share of the guided comparable EPS | about 64% to 65% |
Sources for this section are listed under third-party data below. Price and consensus move daily, so check both with your broker before the release.
What to watch on October 27
- Comparable EPS against $0.82 in Q3 2025, and against a consensus of $0.87 to $0.88. That consensus sits above the roughly $0.84 to $0.86 that the guidance arithmetic suggests, so a result near consensus would put the pressure on the fourth-quarter outlook.
- Unit case volume against a base of +1% in Q3 2025. Q1 and Q2 2026 grew 3% and 5%, each against its own prior-year quarter.
- Organic revenue growth against +6% in Q3 2025, with full-year guidance at about 5% after +10% in Q1 and +6% in Q2.
- Comparable operating margin against 31.9% in Q3 2025, judging the change within the quarter rather than against the higher Q1 and Q2 levels.
- Any change to guidance: comparable EPS growth of 9% to 10%, free cash flow of about $12.4 billion, the 19.9% tax rate, and the timing of the Coca-Cola Beverages Africa sale.
The dividend
On October 15, 2026, the board declared a regular quarterly dividend of $0.53 per share, payable December 15 to shareowners of record at the close of business on December 1. That is $2.12 a year (my calculation). Since U.S. markets moved to one-day settlement in May 2024, the ex-dividend date is normally the same as the record date, which would make it December 1; confirm the date with your broker. This payment is separate from the earnings release, so buying before October 27 or after it does not change it.
For investors in Europe
- KO pays in dollars and U.S. withholding tax applies by default; the rate for non-U.S. investors depends on your broker having a valid Form W-8BEN. See our W-8BEN guide.
- The company expects currency to add about 3% to comparable EPS growth this year, so a move in the dollar affects both reported earnings and the euro value of the dividend.
Sources
- The Coca-Cola Company: Announces Timing of Third Quarter 2026 Earnings Release (September 29, 2026)
- The Coca-Cola Company: Second Quarter 2026 Results and Raised Full Year Guidance (July 28, 2026)
- The Coca-Cola Company: First Quarter 2026 Results, Form 8-K exhibit (April 28, 2026)
- The Coca-Cola Company: Fourth Quarter and Full Year 2025 Results, Form 8-K exhibit (February 10, 2026)
- The Coca-Cola Company: Third Quarter 2025 Results (October 21, 2025)
- The Coca-Cola Company: Board of Directors Declares Regular Quarterly Dividend (October 15, 2026)
- Third-party data (consensus and price), not from the company: Zacks Equity Research via Yahoo Finance (October 22, 2026, 8:15 a.m. EDT); MarketBeat (October 20, 2026); 24/7 Wall St. (October 22, 2026, 1:11 p.m. ET)
Disclaimer: This article is for informational purposes only and does not constitute investment advice. Company figures are taken from the releases listed; consensus and the share price come from the third-party sources listed, as of the times stated; and the second-half and fourth-quarter figures are my own arithmetic, not a company forecast. Investing involves risk, including the possible loss of capital, and a dividend payment is never guaranteed.