
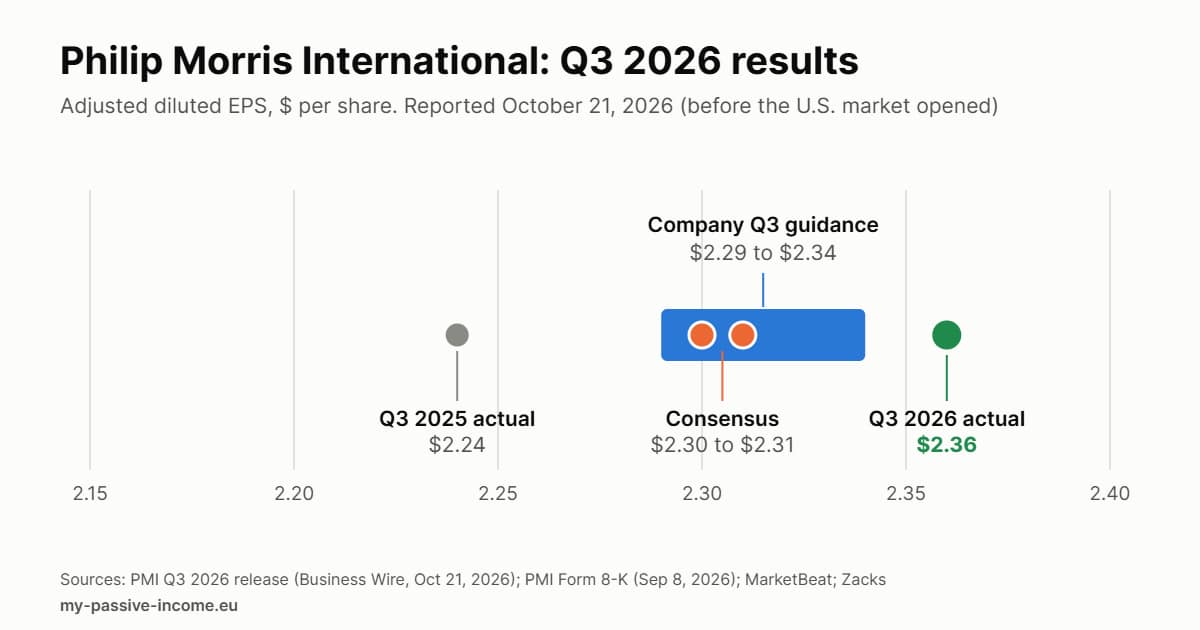
Philip Morris International (NYSE: PM) reported third-quarter 2026 results on October 21, 2026, before the U.S. market opened. Adjusted earnings per share came in at $2.36, above both the company’s own guidance and analyst consensus, while the full-year adjusted EPS forecast was trimmed, solely to reflect currency. Below: the numbers against what we flagged in our preview, the outlook, how the valuation multiples moved, and what is still a question mark.
The quarter in numbers
| Metric | Q3 2026 | Change vs Q3 2025 |
|---|---|---|
| Net revenues | $11,438 million | +5.5% reported, +7.1% organic |
| Adjusted diluted EPS | $2.36 | +5.4% reported, +5.8% excluding currency (currency effect: $0.01) |
| Reported diluted EPS | $2.12 | -4.9% (Q3 2025: $2.23) |
| Adjusted operating income | $5,117 million | +9.6% reported, +10.5% organic |
| Heated tobacco unit shipments (IQOS) | 41.5 billion units | +1.5% |
| ZYN shipments in the U.S. | 3.2 billion pouches | +4.2% |
| U.S. oral smoke-free segment | 3.7 billion units in Q3 (+2.3%) | 10.0 billion units year to date (-5.8%) |
| Smoke-free share of net revenues | more than 40% in Q3 | about 42% year to date |
Source: Philip Morris International third-quarter 2026 release (Business Wire, October 21, 2026, 6:59 a.m. Eastern). The release excerpt I reviewed does not state the reason for the drop in reported EPS, so I do not offer one; check the full release if it matters for your decision.
Against guidance and consensus
| Item | Expected | Actual | Difference |
|---|---|---|---|
| Adjusted EPS vs company guidance (September 8, 2026) | $2.29 to $2.34 | $2.36 | $0.02 above the top of the range |
| Adjusted EPS vs consensus (MarketBeat / Zacks, October 2026) | $2.30 / $2.31 | $2.36 | $0.06 / $0.05 above |
| Net revenues vs consensus (MarketBeat / Zacks) | $11.32 billion / $11.42 billion | $11.438 billion | about 1.0% / 0.2% above |
| Adjusted EPS excluding currency | n/a | $2.37 | $0.01 higher than reported |
This was a modest beat rather than a blowout: $0.02 above the top of the company’s own range, and $0.05 to $0.06 above consensus. Excluding a one-cent currency effect, adjusted EPS would have been $2.37.
Outlook: trimmed for currency only
- Full-year adjusted EPS: $8.29 to $8.44 (up 9.9% to 11.9%), versus $8.35 to $8.50 in the company’s September 8 update. The company says the change is for currency only: the favorable currency effect is now estimated at $0.18, down from $0.24. Excluding currency the range is unchanged at $8.11 to $8.26 (up 7.5% to 9.5%).
- Reported diluted EPS forecast: $7.11 to $7.26, versus $7.28 to $7.43 in September.
- Organic revenue growth: 5% to 7%, with the middle or upper half more likely.
- Organic operating income growth: 7% to 9%, now more likely in the middle or lower half of the range, citing geopolitical cost pressures and U.S. investment.
- ZYN packaging: from the fourth quarter, PMI is moving most flagship ZYN products from 15-pouch to 20-pouch cans. TIKR, citing the CFO on the earnings call, reports that at an unchanged price this means about 25% less revenue per pouch.
- Fourth quarter: the company expects international smoke-free to reaccelerate, plans to increase U.S. ZYN investment, and expects energy-related input price increases to weigh slightly more.
- Cash and balance sheet: operating cash flow of about $13.5 billion, no share buybacks planned in 2026, and a net debt to adjusted EBITDA target of close to 2.0x by year end.
Two soft spots are visible in the numbers: heated tobacco shipments grew only 1.5% in the quarter, and the U.S. oral segment is still down 5.8% year to date despite the Q3 uptick. The ZYN pack change adds a pricing question for the fourth quarter.
The share price and the multiples
PM shares closed at $197.46 on October 21, 2026, down 1.2% on the day, after trading as low as about $194 during the session (TIKR, Benzinga). Benzinga reports that the company pointed to rising energy costs, geopolitical tensions and higher investment in smoke-free products. Using the closing price and the guidance midpoints, the multiples compare as follows (my calculations):
| Measure | Before results (price $204.54, Oct 16; guidance $8.35 to $8.50) | After results (close $197.46, Oct 21; guidance $8.29 to $8.44) |
|---|---|---|
| Forward P/E on the midpoint of full-year adjusted EPS guidance | 24.3x (midpoint $8.425) | 23.6x (midpoint $8.365) |
| Dividend yield on $6.40 a year | 3.13% | 3.24% |
| Annual dividend as a share of guidance midpoint | 76.0% | 76.5% |
Prices: 24/7 Wall St. (October 16, 2026) and TIKR (October 21, 2026 close). Dividend: quarterly $1.60, $6.40 annualized (company, September 2026). Valuation sites that show a higher trailing P/E or payout ratio use reported rather than adjusted earnings.
For investors in Europe
- The $1.60 quarterly dividend (up 8.8% in September) is payable on October 26, 2026. The ex-dividend date was October 2, so buying now does not earn this payment.
- PM pays in dollars and U.S. withholding tax applies by default; the rate for non-U.S. investors depends on your broker having a valid Form W-8BEN. See our W-8BEN guide.
- A stronger dollar helps the euro value of the dividend but, as this quarter and the guidance both show, it also moves PM’s reported earnings.
Sources
- Philip Morris International: 2026 third-quarter and first nine-months results (Business Wire via FinancialContent, October 21, 2026)
- Philip Morris International: 2026 Barclays conference release and currency-only EPS forecast update, Form 8-K exhibit (September 8, 2026)
- Philip Morris International: Q3 2026 results, Form 8-K exhibit (October 21, 2026)
- Philip Morris International: Q3 2025 results, Form 8-K exhibit (October 21, 2025)
- Philip Morris International: September 2026 dividend announcement, Form 8-K
- Benzinga: Why is Philip Morris stock falling Wednesday (October 21, 2026)
- TIKR: Philip Morris beat Q3, then handed it back (October 22, 2026)
- MarketBeat: PM Q3 2026 earnings date and estimates
- Zacks via TradingView: Philip Morris Q3 earnings on deck
- 24/7 Wall St.: Philip Morris just raised its dividend 8.8% (October 16, 2026)
Get new articles by email
Ex-dividend dates, earnings previews and P2P platform changes, straight to your inbox. Unsubscribe anytime.
Disclaimer: This article is for informational purposes only and does not constitute investment advice. Figures are taken from the company release and the third-party sources listed; share prices change continuously and the prices used here are time-stamped as stated. Confirm current figures with your broker or the company’s investor relations page. Investing involves risk, including the possible loss of capital, and a dividend payment is never guaranteed.


