When a company pays you a dividend, the country where it is based may keep part of it before the money reaches your broker. That is dividend withholding tax. The rate in the company’s country is only the starting point: a tax treaty with the country where you live can lower it, an exemption may exist, and your home country may tax the same dividend again. This guide lists the standard rate in eight major markets, taken from each tax authority’s own pages, with the date of the page and what can lower the rate.
All pages were read on 1 November 2026. Tax rules change, so confirm the current rate and your own situation before acting.
Key takeaways:
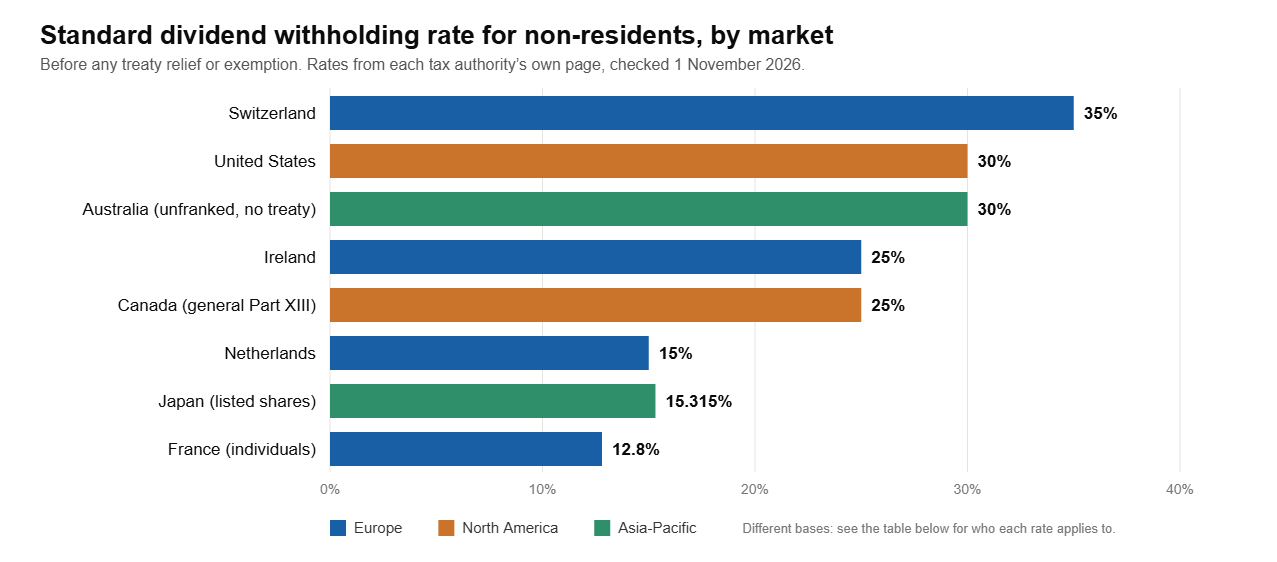
- Among the eight markets covered, the standard rate runs from 12.8% (France, for individuals) to 35% (Switzerland), before any treaty relief.
- A standard rate is not always what you end up paying. The United States withholds 30% unless a lower treaty rate is claimed, and Switzerland’s 35% can be partly or fully refunded to residents of treaty countries.
- Ireland exempts many non-resident individuals who live in an EU/EEA state or a treaty country, but only after a declaration and a certificate of tax residence.
- Fully franked Australian dividends carry no withholding; unfranked ones are taxed at 30% without a treaty.
- The rate on your broker statement can differ from the table below, so always check what was actually withheld.
Watch the video summary
A 70-second video summary of the table below: standard rates, what is left of 100, and how to keep more.
Standard dividend withholding rates for non-residents
| Market | Standard rate | What can lower it | Official page (date) |
|---|---|---|---|
| United States | 30% | A lower tax treaty rate, claimed with Form W-8BEN | IRS (23 Jul 2026) |
| Ireland | 25% (Dividend Withholding Tax) | Exemption for many non-resident individuals living in an EU/EEA state or a treaty country, with a declaration and a certificate of tax residence | Revenue (10 Aug 2026); Tax and Duty Manual 06-08A-01 (Jun 2026) |
| France | 12.8% for individual beneficial owners; 75% on payments made in non-cooperative states or territories | A treaty may lower it; companies are taxed under a different rule | BOFiP BOI-RPPM-RCM-30-30-10-20 (version in force since 29 Jun 2022) |
| Netherlands | 15% | Some foreign recipients are exempt or can reclaim the tax | Belastingdienst (modified 24 Aug 2026) |
| Switzerland | 35% | Generally a final charge for recipients abroad; residents of treaty countries may claim a full or partial refund | Federal Tax Administration (22 Sep 2026) |
| Japan | 15.315% on dividends of listed shares (holders below 3%) | A treaty reduction, requested through the payer before the payment date. The tax agency notes an extra defence special income tax in withholding from 2027 | National Tax Agency (as of 1 Apr 2026) |
| Canada | 25% (general Part XIII rate) | A lower rate or exemption under the Income Tax Act or a tax treaty | Canada Revenue Agency (modified 14 Nov 2025) |
| Australia | 30% on unfranked dividends without a treaty; fully franked dividends are not subject to withholding | Treaties; the tax office says most reduce the rate on unfranked dividends to 15% | ATO (rates) (22 Jun 2026); ATO (franking) (8 Apr 2021) |
The rates are not like for like: France’s 12.8% is for individuals, Japan’s 15.315% is for listed shares, Canada’s 25% is a general rate rather than a dividend-specific one (the agency’s page does not list dividends separately), and Australia’s 30% applies only to the unfranked part. Read the table row by row.
What is left of 100 of dividend
This is our arithmetic on the standard rates above, before any treaty relief, exemption or refund and before tax in your home country:
| Market | Rate used | Left of 100 |
|---|---|---|
| France (individuals) | 12.8% | 87.20 |
| Netherlands | 15% | 85.00 |
| Japan (listed shares) | 15.315% | 84.69 |
| Ireland | 25% | 75.00 |
| Canada | 25% | 75.00 |
| United States | 30% | 70.00 |
| Australia (unfranked, no treaty) | 30% | 70.00 |
| Switzerland | 35% | 65.00 |
Market by market
United States
The IRS says dividends from a US source paid to a nonresident alien are withheld at 30% or a lower tax treaty rate, and that the lower rate is claimed by giving the withholding agent a Form W-8BEN. Our Form W-8BEN guide explains how to fill it in.
Ireland
Revenue states that Irish Dividend Withholding Tax is 25%. Its Tax and Duty Manual lists exempt non-residents, including individuals who are neither resident nor ordinarily resident in Ireland and are tax-resident in a relevant territory, meaning an EU/EEA member state other than Ireland or a country with a double taxation treaty. The exemption is not automatic: it needs a declaration, and individuals also need a certificate of tax residence from their home tax authority.
France
The French tax doctrine sets 12.8% for dividends paid to non-resident individuals who are the beneficial owners, and 75% for payments made in non-cooperative states or territories. Treaties may lower the rate. For companies, the page refers to a different provision and does not state the percentage, so we do not give one.
Netherlands
The Dutch tax administration gives the dividend tax rate as 15%. It says that a recipient outside the Netherlands may, in certain situations, be exempt or reclaim the tax, and it links to separate pages for the conditions.
Switzerland
The Swiss Federal Tax Administration lists the withholding tax on dividends and interest at 35%. For recipients living abroad it is generally a final charge, but where the recipient’s country has a double taxation agreement with Switzerland, a full or partial refund may be possible depending on the agreement.
Japan
The National Tax Agency lists 15.315% for dividends of listed shares, with an exception for holders of 3% or more of the shares or capital. A treaty reduction is requested with a notification filed through the payer, no later than the day before the payment date. The agency also notes that a defence special income tax is added to withholding from 2027, so check the rate again then.
Canada
The Canada Revenue Agency states a general Part XIII rate of 25% on amounts paid to non-residents, which can be lowered or removed under the Income Tax Act or a bilateral tax treaty. The 25% still applies to residents of countries without a treaty or whose treaty is not yet in effect.
Australia
The Australian Taxation Office says that where there is no treaty, withholding on unfranked dividends is 30%, and that most agreements reduce it to 15%. It also says no tax has to be withheld on dividends that are fully franked or that are conduit foreign income.
How to keep more of your dividend
- Use the paperwork the market offers: Form W-8BEN for US dividends, a treaty notification in Japan, an exemption declaration in Ireland.
- Look into refunds where the country offers them, such as Switzerland for residents of treaty countries and the Netherlands in some situations.
- Check what your broker actually withheld. The standard rate is a starting point, and the amount on your statement can differ.
- Remember your own country: it may tax the dividend again, often with a credit for tax withheld abroad. Rules differ, so check your tax authority.
- For ETFs, the fund’s domicile and structure matter as well. See our low-cost ETF comparison.
Markets not covered yet
The United Kingdom, Germany, Italy, Spain, Denmark and other large dividend markets are not in this table. We publish only rates we could confirm on the tax authority’s own pages, and for these markets we have not yet done so. Their absence says nothing about their rates. We will add them as we verify them.
Sources
All read on 1 November 2026: IRS, federal income tax withholding on other kinds of US-source income paid to nonresident aliens (23 Jul 2026). Revenue, dividend income (published 10 Aug 2026) and Tax and Duty Manual 06-08A-01, Dividend Withholding Tax (updated Jun 2026). BOFiP-Impots, BOI-RPPM-RCM-30-30-10-20 (version in force since 29 Jun 2022). Belastingdienst, dividend tax if you receive dividend (modified 24 Aug 2026). Swiss Federal Tax Administration, Verrechnungssteuer (updated 22 Sep 2026). National Tax Agency of Japan, No. 2884 (as of 1 Apr 2026). Canada Revenue Agency, rates for Part XIII tax (modified 14 Nov 2025). Australian Taxation Office, interest, unfranked dividends and royalties (22 Jun 2026) and withholding from dividends paid to foreign residents (8 Apr 2021).
Get new articles by email
Ex-dividend dates, earnings previews and P2P platform changes, straight to your inbox. Unsubscribe anytime.
Informational only, not investment, tax or legal advice. Tax rules and treaty rates change, and your own situation decides what applies to you. Confirm the current rate with the tax authority or a qualified adviser before acting.