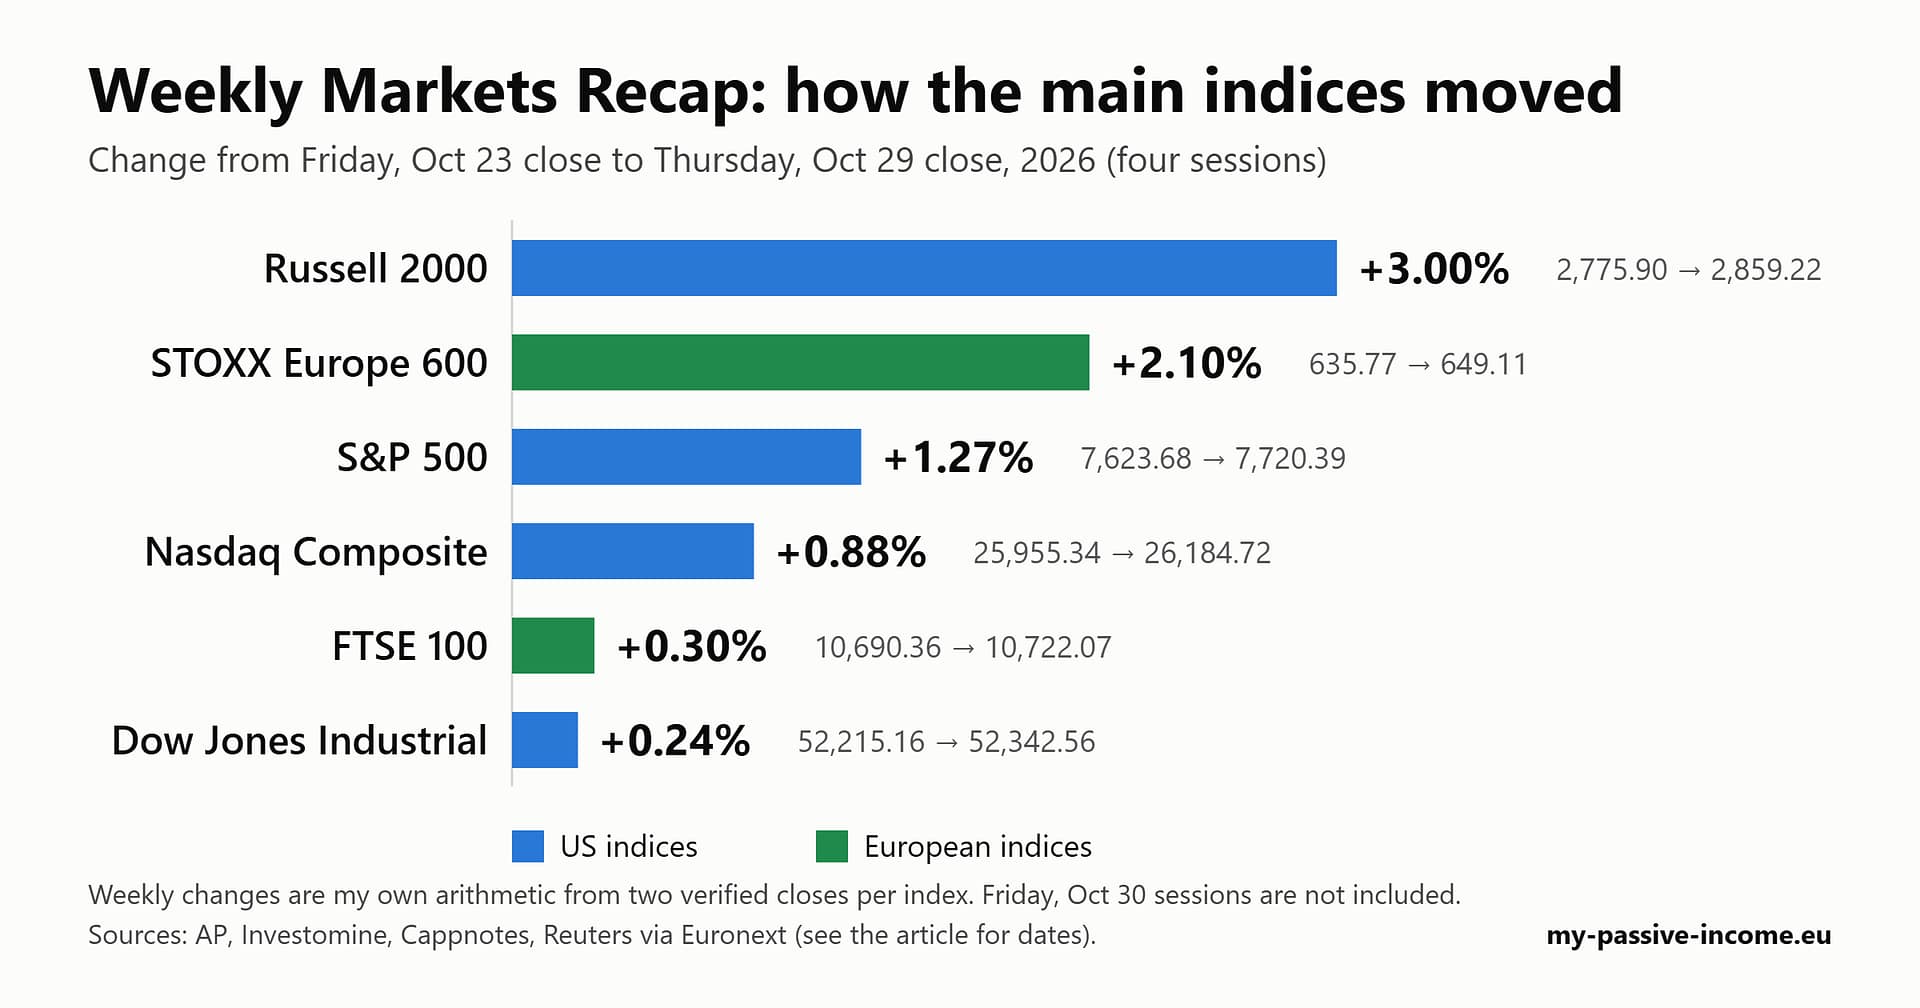
Wall Street ended Friday, October 30, 2026, with its worst day since June: the S&P 500 fell 1.82% to 7,580.07, the Nasdaq Composite lost 2.86% to 25,437.00, the Dow Jones Industrial Average slipped 1.09% and the Russell 2000 dropped 1.66%. Intel plunged about 29% after its fourth-quarter outlook, and worries about AI spending, higher borrowing costs and Fed comments favouring higher rates added to the pressure. Today, Monday, November 2, 2026, US futures are pointing higher, South Korean and Chinese stocks rebounded, oil is down about 3% on Qatar-mediated talks over the Strait of Hormuz, and Apple and Palantir report after the close. Data cut-off: 09:05 UTC (11:05 in Bucharest). The freshest source timestamps are 08:26 (Investinglive, time zone not stated), 07:01 (TradingKey, time zone not stated), 06:21 (XTB, time zone not stated) and 05:29 UTC (AP), so futures and oil may have moved since.
Friday, October 30: how the main indices closed
| Index | Close | Change on the day |
|---|---|---|
| S&P 500 | 7,580.07 | -140.32 points (-1.82%) |
| Dow Jones Industrial Average | 51,770.31 | About -572 points (-1.09%) |
| Nasdaq Composite | 25,437.00 | -747.73 points (-2.86%) |
| Russell 2000 | 2,811.84 | -47.37 points (-1.66%) |
| Nasdaq 100 | n/a | -3.46% (third correction of the year, per one source) |
| STOXX Europe 600 | 646.75 | -0.36% (our arithmetic; Saxo says -0.4%) |
| DAX | About 25,818 | -0.9% (Saxo) |
| FTSE 100 | 10,729.78 | +0.07% |
| CAC 40 | 7,969.42 | -0.01% |
| Nikkei 225 (Friday close) | 63,290.11 | -2.12% (our arithmetic; Investomine says -2.1%) |
Sources: the US closes come from AP via La Nación (published October 30, 2026, 20:32 UTC), which matches Investrade (October 30, 2026, 20:14 UTC) and The Wall Street Republic (page last modified 22:59 UTC). The Dow’s point change differs slightly by source: AP-based figures give -572.25, Yahoo Finance gives -572.29 (close at 20:47:53 UTC) and Investrade gives -571.95, so we show “about -572”. The Nasdaq 100 move is from The Wall Street Republic and XTB. European and Nikkei levels are from Investomine (published November 1, 2026); the percentages are our arithmetic against Thursday’s closes in our previous edition and agree with Saxo Morning Brew (November 2, 2026) (STOXX 600 -0.4%, DAX -0.9%) and Saxo Asia Market Quick Take (November 2, 2026) (FTSE 100 +0.07%, CAC 40 -0.01%). The DAX level is Investomine’s approximate figure. Market-data summaries, not exchange files, so the last decimal may differ.
Rates, oil, gold and currencies
| Market | Friday close / settlement | This morning |
|---|---|---|
| US 10-year Treasury yield | About 4.93% (sources range 4.91% to 4.94%) | About 4.93% to 4.95% |
| US 2-year Treasury yield | About 4.58% to 4.60% | About 4.60% |
| US 30-year Treasury yield | About 5.31% to 5.33% | About 5.33% |
| WTI crude (December) | $104.12 (+2.08%) | About $100.5 to $100.6 (-3.3%) |
| Brent crude (January contract) | $113.43 (+$2.63) | About $109.7 (-3.3%) |
| Brent crude (December, expiring) | $117.64 | n/a |
| Gold | Dec futures $3,898.90 (-3.29%, a 52-week low); spot about $3,881 | About $3,903 to $3,916 (+0.7% to +1.1%) |
| Silver | Dec futures $49.28 (-5.93%) | About $49.85 to $50.40 |
| EUR/USD | About 1.116 | 1.1159 to 1.1184 |
| USD/JPY | n/a | 157.73 to 157.91 |
| VIX | 19.42 (+12.9%); spiked to 23.93 intraday | About 19.4 (VIX futures, XTB) |
Sources: Friday settlements from Investrade, The Wall Street Republic (oil, yields), Investomine (spot gold, EUR/USD, December Brent) and Yahoo Finance (VIX). Morning figures from AP via News4Jax (November 2, 2026, 05:29 UTC), Saxo Morning Brew, Saxo Asia Market Quick Take, XTB Morning Wrap (November 2, 6:21, time zone not stated) and NordFX Market Pulse (November 2, 2026). The gap between the December and January Brent contracts (about $4) reflects the December contract’s expiry, so compare Brent only within the same contract; AP’s -3.3% matches the January contract. Yield sources disagree by up to three basis points and are shown as ranges. Saxo says gold fell 12.7% in October.
What moved markets on Friday
AI spending and Intel. Yahoo Finance attributes the sell-off to renewed worries about Big Tech’s AI spending after this week’s Amazon and Alphabet earnings, Intel’s weak outlook, rising borrowing costs and Fed officials’ comments favouring higher rates. Nasdaq fell about 5.2% in October, its worst month since March 2025 according to Yahoo. Intel’s own release (October 29, 2026, 4:01 p.m. EDT) shows third-quarter revenue of $16.5 billion (up 21% from $13.65 billion) and non-GAAP earnings of $0.52 per share (versus $0.23), but a fourth-quarter outlook of $15.0 to $16.0 billion in revenue, non-GAAP EPS of $0.25 (GAAP $0.10) and a non-GAAP gross margin of 38.0%. According to The Wall Street Republic, the shares fell 28.58% to $65.76 from $92.07, and Investrade calls it the stock’s steepest one-day drop on record. Saxo also lists Reddit at -29.2% and AMD at -10.9%; AMD reports on Tuesday.
Big Tech. The Wall Street Republic has Amazon down 1.41% to $240.35 and Apple down 1.23% to $344.63; Yahoo puts Amazon’s fall at about 2%, so the size of the move depends on the source. Saxo cites Goldman Sachs estimates of hyperscaler capital spending near $800 billion in 2026 and $1.2 trillion in 2027, with S&P 500 earnings growth slowing from nearly 30% to 18% (a bank estimate, not a result).
Energy and the Fed. Exxon Mobil and Chevron reported adjusted third-quarter earnings of $4.23 and $5.28 per share (Investrade), against $1.88 and $1.85 in the third quarter of 2025, and their shares closed up 2.16% and 1.75% (The Wall Street Republic). Oil rose on Friday after a reported tanker attack near the Strait of Hormuz. On rates, Saxo says futures imply a 72% probability of a quarter-point Fed hike in December, and Investomine notes that both dissenters in last week’s 10-2 hold favoured a hike. These are market-implied odds and press summaries, not Fed statements.
Gold. Gold’s Friday drop of 3.3% to a 52-week low (Investrade) came with the 10-year yield at about 4.9%. Saxo attributes the slide to technical selling, reduced risk appetite and energy-driven inflation.
Overnight in Asia and Europe’s open
Asia was mixed. TradingKey (November 2, 07:01, time zone not stated) has the Nikkei 225 closing down 0.33% at 63,081.64, in line with our arithmetic against Friday’s 63,290.11, while AP (05:29 UTC) caught an earlier reading of -0.1% at 63,218.02. Kioxia fell 15.8% to 11,345 yen after weak earnings guidance and SoftBank fell 1.6%. The Kospi jumped 2.24% to 5,859.08 (AP: +2.3%) as SK Hynix rose 4.5% and Samsung Electronics 1.8%; TradingKey cites South Korea’s October semiconductor exports up 259% from a year earlier and a government plan for 21.3 trillion won of spending on chips and AI. The Kospi is still down more than 16% over the past month (AP). The Shanghai Composite gained 1.2% to 3,640.93, the Hang Seng 0.6% to 23,437.41 and Australia’s ASX 200 lost 0.6% to 8,851.40. China’s official manufacturing PMI was 49.3 for October (NordFX), i.e. in contraction, and XTB reports that the People’s Bank of China moved to daily overnight repo operations at 1.25%, injecting 541 billion yuan, and convened regulators on share buybacks.
Early European trading was subdued: per Investinglive (08:26, time zone not stated), the DAX and CAC 40 were down 0.2%, the FTSE 100 down 0.3%, the Euro Stoxx 50 flat and Spain’s IBEX up 0.6%, with S&P 500 futures up about 0.3% and Nasdaq futures up about 0.7%. Saxo had futures at +0.5% and +0.9% earlier in the morning.
Iran and oil. According to AP, Iran’s top diplomat said negotiators were in Qatar on a proposal that could reopen the Strait of Hormuz within two days if the US meets several conditions, and that no direct talks with the US were taking place. XTB adds that President Trump said he is “in no rush” and that UKMTO has confirmed at least 10 incidents involving tankers since October 31. Goldman Sachs raised its December Brent forecast to $105 from $90, and OPEC+ kept its December production targets unchanged (XTB). Brent is down about 3.3% to around $109.7 this morning; Saxo notes concern about possible US military action against Iran after Tuesday’s midterm elections. These are press reports of an unresolved negotiation and could reverse quickly.
Monday, November 2: what is scheduled
| Time (UTC / Bucharest / ET) | Event | Consensus | Previous / result |
|---|---|---|---|
| Already out | China official manufacturing PMI, October | Not found | 49.3 (below 50) |
| 08:15 to 09:30 UTC / 10:15 to 11:30 / 3:15 to 4:30 a.m. ET (XTB lists CET) | Final manufacturing PMIs: Spain, Italy, France, Germany, euro area, UK | 50.4 / 49.9 / 49.3 / 54.2 / 52.4 / 52.8 | Not found |
| 12:00 UTC / 14:00 / 7:00 a.m. ET | Speech by Bundesbank President Joachim Nagel | n/a | n/a |
| 14:45 UTC / 16:45 / 9:45 a.m. ET | US final S&P Global manufacturing PMI, October | 56.0 | Not found |
| 15:00 UTC / 17:00 / 10:00 a.m. ET | US ISM Manufacturing PMI, October (plus prices paid and construction spending) | 54.5; prices paid 77.2; construction spending +0.4% m/m | Not found |
| Before the open (Marriott 8:00 a.m., IDEXX 8:30 a.m. ET calls) | Marriott, IDEXX results, EPS | $2.87; $3.71 | $2.47; $3.40 (year-ago) |
| After the close (call 5:00 p.m. ET = 22:00 UTC = midnight Bucharest) | Apple fiscal Q4 results, EPS | About $1.98 to $2.00; revenue about $113 billion | $1.85 (year-ago) |
| After the close | Palantir Q3 results, EPS | $0.33 | $0.18 (year-ago); company revenue guidance $2.160 to $2.164 billion |
| After the close (4:30 p.m. / 5:00 p.m. ET calls) | Vertex Pharmaceuticals; Realty Income | Vertex EPS $4.36; Realty Income n/a | Vertex $4.22 (year-ago) |
Sources: the Apple call time is from Apple Investor Relations; Apple consensus from Stock Titan (Nasdaq data as of October 30, 2026, 4:01 a.m. ET) and Saxo, which differ slightly, and the macro consensus figures from XTB. Stock Titan counts 86 earnings reports today, 18 before the open and 58 after the close; others include Estée Lauder, Ryanair, onsemi and Roku. Palantir’s $2.160 to $2.164 billion is the company’s own guidance, not an analyst consensus. Company report dates and times other than Apple’s have not been confirmed with the companies.
The next trading days
According to Saxo Morning Brew (November 2, 2026): on Tuesday, November 3, the Reserve Bank of Australia decision, the US midterm elections and earnings from AMD, Amgen, Arista, Pfizer and Eaton; on Wednesday, November 4, US ADP and ISM services data, the US Treasury’s quarterly borrowing plans and earnings from Novo Nordisk, Toyota, Qualcomm, Arm, McDonald’s and Uber; on Thursday, November 5, the Bank of England decision; and on Friday, November 6, US nonfarm payrolls. Saxo expects the RBA, the Riksbank and the Bank of England to raise rates this week, which is a forecast, not a decision. Investomine also lists the September JOLTS job-openings report on Tuesday. See our McDonald’s Q3 2026 earnings preview for November 4, and our weekly markets recap for last week’s context.
Sources
- Intel: third-quarter 2026 financial results (October 29, 2026)
- Apple Investor Relations: FY26 fourth-quarter results event (conference call Monday, November 2, 2026, 2:00 p.m. PT)
- Market-data summaries and news, not primary sources: AP via La Nación (October 30, 2026, 20:32 UTC); Investrade Market Review (October 30, 2026, 20:14 UTC); The Wall Street Republic (October 30, 2026); Yahoo Finance live blog (October 30, 2026); Investomine weekly report (published November 1, 2026); Saxo Morning Brew (November 2, 2026); Saxo Asia Market Quick Take (November 2, 2026); AP via News4Jax (November 2, 2026, 05:29 UTC); TradingKey (November 2, 2026, 07:01); XTB Morning Wrap (November 2, 2026, 6:21); NordFX Market Pulse (November 2, 2026); Investinglive (November 2, 2026, 08:26); Stock Titan earnings calendar (October 30, 2026). All pages were read on November 2, 2026, between 08:56 and 09:05 UTC.
Get new articles by email
Ex-dividend dates, earnings previews and P2P platform changes, straight to your inbox. Unsubscribe anytime.
Disclaimer: This article is for informational purposes only and does not constitute investment advice. Figures come from the sources listed, as of the times stated, and may be revised. Market-data summaries can differ slightly from official exchange figures. Confirm current prices with your broker. Investing involves risk, including the possible loss of capital.