Wall Street ended mixed on Tuesday, November 3, 2026: the S&P 500 rose 0.36% to 7,568.92 and the Nasdaq Composite gained 0.83% to 25,372.01 as chip stocks rebounded, while the Dow Jones Industrial Average fell 0.38% to 51,786.72 with Apple lower. European stocks closed lower (STOXX 600 -0.58%, FTSE 100 -1.14%). After the close AMD reported record revenue and its shares rose about 6.6% to 8% in after-hours trading. Overnight, US midterm results pointing to Democratic gains hit AI-linked stocks in Asia: the Nikkei 225 closed 1.42% lower after falling more than 3% earlier. Today, Wednesday, November 4, 2026, the euro-area flash inflation estimate, ADP jobs, ISM services and the US Treasury’s quarterly refunding are due; CVS, Uber and McDonald’s report before the US open and Qualcomm and Arm after the close. Data cut-off: 07:45 UTC (09:45 in Bucharest). The freshest source timestamps are Reuters (06:39 GMT), ICMarkets (06:18 UTC) and Zaikei (06:31 UTC), so futures, oil and European prices may have moved since.
Tuesday, November 3: how the main indices closed
| Index | Close | Change on the day |
|---|---|---|
| S&P 500 | 7,568.92 | +27.52 points (+0.36%) |
| Dow Jones Industrial Average | 51,786.72 | -197.26 points (-0.38%) |
| Nasdaq Composite | 25,372.01 | +207.65 points (+0.83%) |
| Russell 2000 | 2,812.45 | +6.57 points (+0.23%) |
| Nasdaq 100 | 28,180.26 to 28,184 | +0.68% to +0.7% (Capp Notes, Saxo) |
| STOXX Europe 600 | 645.66 | -0.58% (Saxo rounds to -0.6%) |
| Euro Stoxx 50 | 6,144.56 | -0.51% (-31.50 points; single source) |
| DAX | 25,864.62 | -0.45% |
| CAC 40 | 8,020.31 | -0.34% |
| FTSE 100 | 10,638.43 | -1.14% |
| Nikkei 225 | Closed Tuesday (holiday) | Wednesday close: 62,188.63, -1.42% (see Asia below) |
Sources: the US closes come from AP via La Nación (page metadata: November 3, 2026, 21:22 UTC) and Capp Notes (last modified 22:33 UTC); the S&P 500 and Dow levels also match the Saxo Asia Market Quick Take (November 4), and the percentage changes match Stock Titan, TheStreet and Yahoo Finance. The Russell 2000 change is +0.23% in Capp Notes and +0.2% in AP. European closes: the STOXX 600 and FTSE 100 are from Capp Notes and Saxo (and the FTSE 100 from ad-hoc-news); the DAX from ad-hoc-news and Saxo; the CAC 40 from Orange (published 18:50 French time), with a second headline at -0.34% on JKN; the Euro Stoxx 50 from ad-hoc-news only (published 19:09), so treat it as unconfirmed. Market-data summaries, not exchange files, so the last decimal may differ.
Rates, oil, gold and currencies
| Market | Monday close (previous edition) | Tuesday close | This morning |
|---|---|---|---|
| US 10-year Treasury yield | About 4.89% to 4.91% | 4.95% (+4 bp) | About 4.94% to 4.96% |
| US 2-year Treasury yield | About 4.60% | 4.61% (+2 bp) | n/a |
| US 30-year Treasury yield | About 5.29% | 5.32% (+4 bp) | n/a |
| German 10-year Bund yield | n/a | 3.330% (+3.8 bp) | About 3.35% |
| UK 10-year gilt yield | n/a | 5.261% (+5.9 bp; single source) | n/a |
| WTI crude (December) | $96.46 | $96.09 (-0.38%) | $95.45 to $96.59 |
| Brent crude (January) | $104.77 | $103.60 (-1.12%) | $103.14 to $104.42 (contract month not stated in the morning reports) |
| Gold (futures) | Sources conflict | $3,931.90 (-0.95%); Saxo has about $3,940 (-0.7%) | About $3,958.50 (+0.5%) |
| EUR/USD | n/a | n/a | 1.1241 to 1.1249 |
| USD/JPY | n/a | 158.66 | 157.63 to 157.76 |
| Dollar index (DXY) | n/a | 101.87 (+0.12%) | n/a |
| VIX | 21.15 | 20.83 (-1.51%) | n/a |
Sources: Tuesday’s yields, oil, gold, VIX and currencies are from Capp Notes (22:33 UTC); Saxo agrees on yields and oil within a few basis points or cents and gives gold at about $3,940. Morning readings are from AP via News4Jax (04:13 UTC), Euronews (05:47 UTC) and Reuters via Business Recorder (Brent at 05:10 GMT), so each is a range rather than one price. Monday’s column is taken from our previous edition, where gold sources already disagreed, so no like-for-like gold change is shown.
What moved markets on Tuesday
Chips rebound, Apple weighs on the Dow. According to Capp Notes, technology rose 1.31% and communication services 1.18%, while consumer staples fell 2.07%, materials 2.01% and energy 0.85%. Investopedia via Yahoo Finance reports Nvidia up 2%, Broadcom up 3% and the iShares Semiconductor ETF up 2.5% after a drop of about 10% over three days (XTB gives the same 10%). Apple fell about 1.9% after forecasting weaker margins on memory costs, which dragged on the Dow (Stock Titan); Saxo adds that Nvidia overtook Apple as the world’s most valuable company, which we have not verified. Palantir fell about 1.65% on slowing new contract bookings despite beating estimates, and Shopify fell 8.74% at the close after revenue just missed estimates (Stock Titan; TheStreet reported a 16% fall in early trading and gross merchandise volume of $119.1 billion against about $120 billion expected).
Strong jobs data, higher yields. According to Capp Notes (a single source), September JOLTS job openings rose 333,000 to 7.523 million against a forecast of about 7.15 million, quits were 3.36 million (the highest since March 2025) and layoffs 1.64 million (the lowest since March 2025), and factory orders rose 1.8% against +1.3% expected. The 10-year yield rose to 4.95%. Stock Titan reports that two Fed presidents said rates may need to rise; we could not identify them.
Oil and Iran. Brent settled 1.12% lower at $103.60 on hopes of a US-Iran deal (Stock Titan, Capp Notes), after Monday’s 7.6% drop. This morning Reuters has Brent up 0.8% at $104.42 (05:10 GMT): a senior Iranian official described a deal as far off, the US carried out limited ‘defensive’ strikes on Qeshm Island, and API data showed US crude stocks falling 5.27 million barrels in the week to October 30 against an expected rise of about 0.88 million. A Reuters headline list also says Iran’s Revolutionary Guards reported four tankers ablaze after hitting mines near the Strait of Hormuz; we have not confirmed that. These are press reports of an unresolved situation and could reverse quickly.
Europe. Stocks lost ground and the FTSE 100 snapped a four-day winning streak as miners and banks weighed (BBN Times). Newsquawk (15:20 UTC, before the close) had health care leading and basic resources lagging, and lists Schaeffler’s plan to close five European sites with 3,460 job cuts and Ferrari’s third-quarter beat but miss on full-year EPS guidance.
After the close: AMD and other results
AMD (AMD press release, November 3, 2026): third-quarter revenue of $13.377 billion, up 45% from a year earlier; data-center revenue of $8.546 billion, up 97%; non-GAAP EPS of $2.09 (GAAP $1.46); and non-GAAP gross margin of 56%. It guided fourth-quarter revenue to about $17 billion, plus or minus 3%, with non-GAAP gross margin of about 55%. Revenue was above the roughly $13.0 billion plus or minus $0.3 billion guidance we cited in our previous edition (from Hudson Labs). Shares rose about 6.6% (Stock Titan, 7 p.m. ET) to 8% (TheStreet, 11:33 p.m. EST) after hours; we have not read the call transcript. Press summaries from Stock Titan (7 p.m. ET), not company releases: Arista Networks +10.9% on revenue of about $3.66 billion, Skyworks -17% on its December-quarter guidance, and Amdocs down more than 40% on a fiscal 2027 revenue forecast tied to a dispute with T-Mobile.
Overnight: midterms, Asia and Europe’s open
Midterms. Euronews, citing the Associated Press, reports (06:47 CET) that Democrats won control of the Senate and are on course to take the House; the Reuters Europe-open report says Democrats won both chambers. Trump said he would block Democratic legislation. Reuters says investors fear tighter AI regulation, including oversight of data-centre construction, could dampen investment; Pepperstone’s Chris Weston told AFP a narrow Democratic win may already be priced in.
Asia. The Nikkei 225 closed at 62,188.63, down 893.23 points (-1.42%), and the TOPIX at 3,895.38 (-0.89%) (Zaikei, 15:31 JST). Earlier Reuters (01:50 GMT) had the Nikkei down 3.1% with Kioxia, SoftBank, Advantest and Tokyo Electron among the biggest decliners, and AP (04:13 UTC) had it down 3.6%. The Kospi closed up 0.62% at 5,683.80 after swinging between 5,421.72 and 5,828.13 (Asiae, Seoul Shinmun), a day after its 3.59% fall (Capp Notes). For Hong Kong, Shanghai, Australia and Taiwan we only found mid-session readings, which are not closes: the Hang Seng -0.2%, Shanghai Composite -0.1%, ASX 200 -0.8% and Taiex -2.3% (AP, 04:13 UTC).
Futures and Europe’s open. US futures were lower overnight, but sources differ on how much: ICMarkets (06:18 UTC) had S&P 500 futures down about 1.2%, Nasdaq-100 futures about 2% and Dow futures 412 points, while a Minkabu report (05:13 UTC) said losses had narrowed. European futures were milder: STOXX 600 -0.2%, DAX -0.2% and FTSE 100 -0.4% (Reuters, 06:39 GMT). Novo Nordisk reported before the market (company release, 06:30 UTC): third-quarter sales up 4% at constant exchange rates, adjusted operating profit of DKK 31.72 billion (+27% at constant rates) and a raised 2026 outlook; we found no price reaction at the cut-off. Reuters also notes that BMW’s third-quarter earnings fell.
Wednesday, November 4: what is scheduled
| Time (UTC / Bucharest / ET) | Event | Consensus | Previous / result |
|---|---|---|---|
| Already out | Novo Nordisk Q3 results | n/a | Adjusted operating profit DKK 31.72 bn (+27% at constant rates); 2026 outlook raised |
| Already out | API crude inventories, week to October 30 | +0.88 million barrels | -5.27 million barrels (Reuters) |
| 08:30 / 10:30 / 03:30 | Riksbank policy decision | 25 bp hike to 2.00% (Newsquawk preview) | Release time not stated in the preview; press conference at 10:00 GMT |
| 08:50 to 09:30 / 10:50 to 11:30 / 03:50 to 04:30 | Final October services PMIs: France, Germany, euro area, UK | n/a | n/a |
| 10:00 / 12:00 / 05:00 | Euro-area flash HICP inflation, October, year on year | About 4.0%; core about 2.5% (single source) | Previous 3.8% (Eurostat, September) |
| 11:30 / 13:30 / 06:30 | CVS Health Q3, EPS / revenue | $1.65 / $104.72 billion | n/a |
| 11:55 / 13:55 / 06:55 | Uber Q3, EPS / revenue | $0.86 / $14.66 billion | n/a |
| 12:00 / 14:00 / 07:00 | McDonald’s Q3, EPS / revenue | $3.38 / $7.28 billion | n/a |
| 13:15 / 15:15 / 08:15 | US ADP employment, October | 65,000 to 70,000 | About 90,000 (September) |
| 13:30 / 15:30 / 08:30 | US trade balance, September | Deficit near $108 billion | n/a |
| About 13:30 (time not confirmed) | US Treasury quarterly refunding announcement | Dealers expect coupon auction sizes unchanged; 20- and 30-year cuts expected in 2027 (Reuters, November 2) | n/a |
| 14:45 / 16:45 / 09:45 | Final S&P Global US services PMI | n/a | n/a |
| 15:00 / 17:00 / 10:00 | US ISM services PMI, October | About 54.8 | Previous 54.9; prices index about 74.0 |
| 15:30 / 17:30 / 10:30 | EIA crude oil inventories | n/a | n/a |
| 21:00 / 23:00 / 16:00 | Qualcomm fiscal Q4, EPS / revenue | $2.16 / $10.12 billion | n/a |
| 21:05 / 23:05 / 16:05 | Arm Holdings, EPS / revenue | $0.47 / $1.38 billion | n/a |
| Overnight | US midterm results continue to come in | n/a | n/a |
Sources: macro times are from Techflow (times in UTC+8, converted) and Traderfactor (published 04:49 UTC; ET times, consensus figures single-source); the Riksbank expectation is from the Newsquawk preview (November 3, 13:27 UTC); the refunding expectation from Reuters via Investing.com (November 2); the previous euro-area rate from Eurostat; company times and consensus from Newsquawk (November 3, 17:20 UTC), which labels times EST, assumed here as ET (UTC-5). Bucharest times assume UTC+2. Consensus figures can change before the release. See our McDonald’s and Qualcomm earnings previews.
The next trading days
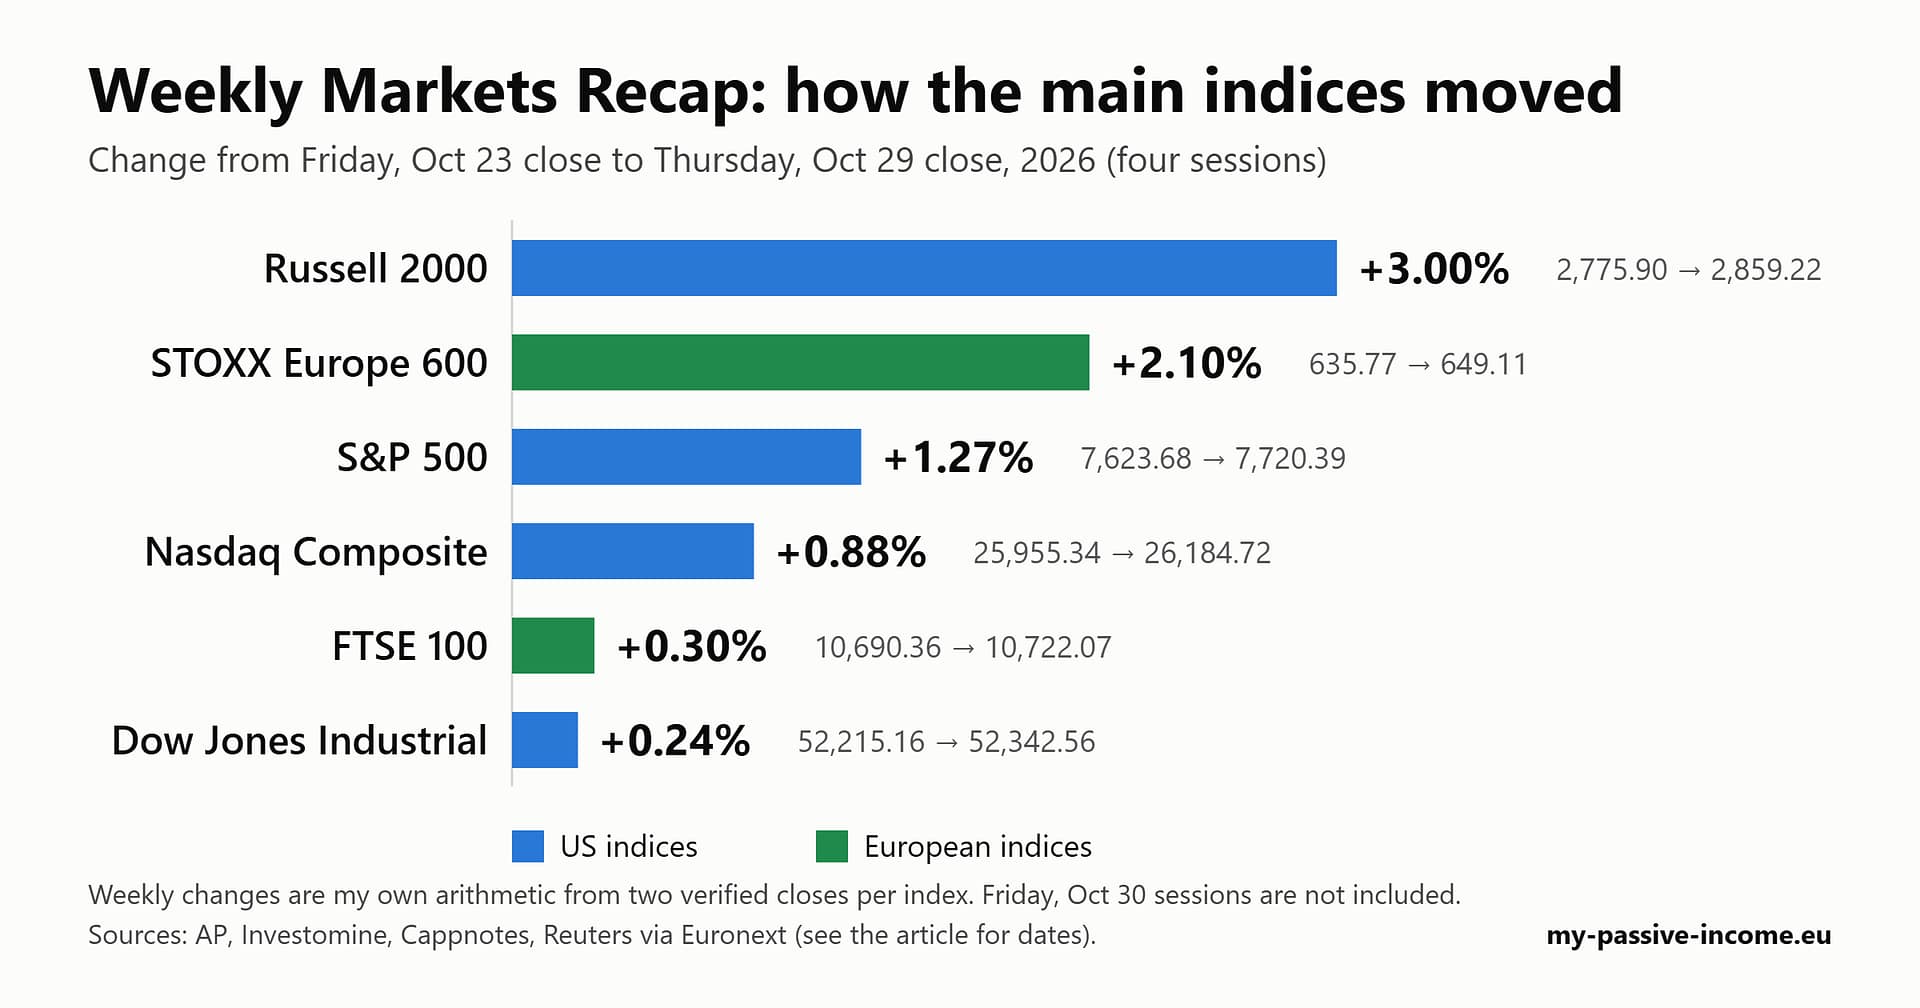
On Thursday, November 5, our previous edition (citing Saxo) listed the Bank of England decision, with Saxo expecting a hike (a forecast, not a decision), and Saxo’s November 4 note lists earnings from Toyota, Sony, Airbnb, Marriott, Booking and Lumentum; see our ConocoPhillips preview. On Friday, November 6, US October payrolls are due, with consensus of about 55,000 to 65,000 jobs depending on the source, as cited in the previous edition. See also our weekly markets recap.
Sources
- AMD: third-quarter 2026 results (press release, November 3, 2026)
- Novo Nordisk: Q3 2026 results (company announcement, November 4, 2026, 06:30 UTC)
- Eurostat: euro area annual inflation, September 2026
- Market-data summaries and news, not primary sources: AP via La Nación (November 3, 2026); Capp Notes closing look (November 3, 2026, 22:33 UTC); Stock Titan live blog (November 3, 2026, last updated 7:07 p.m. ET); TheStreet (November 3, 2026, update 11:33 p.m. EST); Yahoo Finance / Investopedia (November 3, 2026); Saxo Asia Market Quick Take (November 4, 2026; page metadata inconsistent, figures match AP and Capp Notes); XTB Daily Summary (November 3, 2026, 7:19 p.m.); ad-hoc-news: DAX close; ad-hoc-news: Euro Stoxx 50 close; ad-hoc-news: FTSE 100 close; BBN Times: FTSE 100; Orange: Bourse de Paris close (November 3, 2026); JKN: CAC 40 close; Newsquawk European market wrap (November 3, 2026, 15:20 UTC); Newsquawk US earnings estimates (November 4, 2026); Newsquawk Riksbank preview (November 3, 2026); Euronews (November 4, 2026, 06:47 CET); AP via News4Jax (November 4, 2026, 04:13 UTC); Reuters via Business Recorder: oil (November 4, 2026, 05:10 GMT); Reuters via Business Recorder: Nikkei (November 4, 2026, 01:50 GMT); Reuters: Europe set to open lower (November 4, 2026, 06:39 GMT); Zaikei: Nikkei close (November 4, 2026, 15:31 JST); Asiae: Kospi close; Seoul Shinmun: Kospi close; ICMarkets (November 4, 2026, 06:18 UTC); Minkabu (November 4, 2026, 14:13 JST); Traderfactor (November 4, 2026, 04:49 UTC); Techflow calendar (November 3, 2026); Reuters via Investing.com: Treasury refunding (November 2, 2026). All pages were read on November 4, 2026, between about 07:37 and 07:46 UTC.
Get new articles by email
Ex-dividend dates, earnings previews and P2P platform changes, straight to your inbox. Unsubscribe anytime.
Disclaimer: This article is for informational purposes only and does not constitute investment advice. Figures come from the sources listed, as of the times stated, and may be revised. Market-data summaries can differ slightly from official exchange figures. Confirm current prices with your broker. Investing involves risk, including the possible loss of capital.