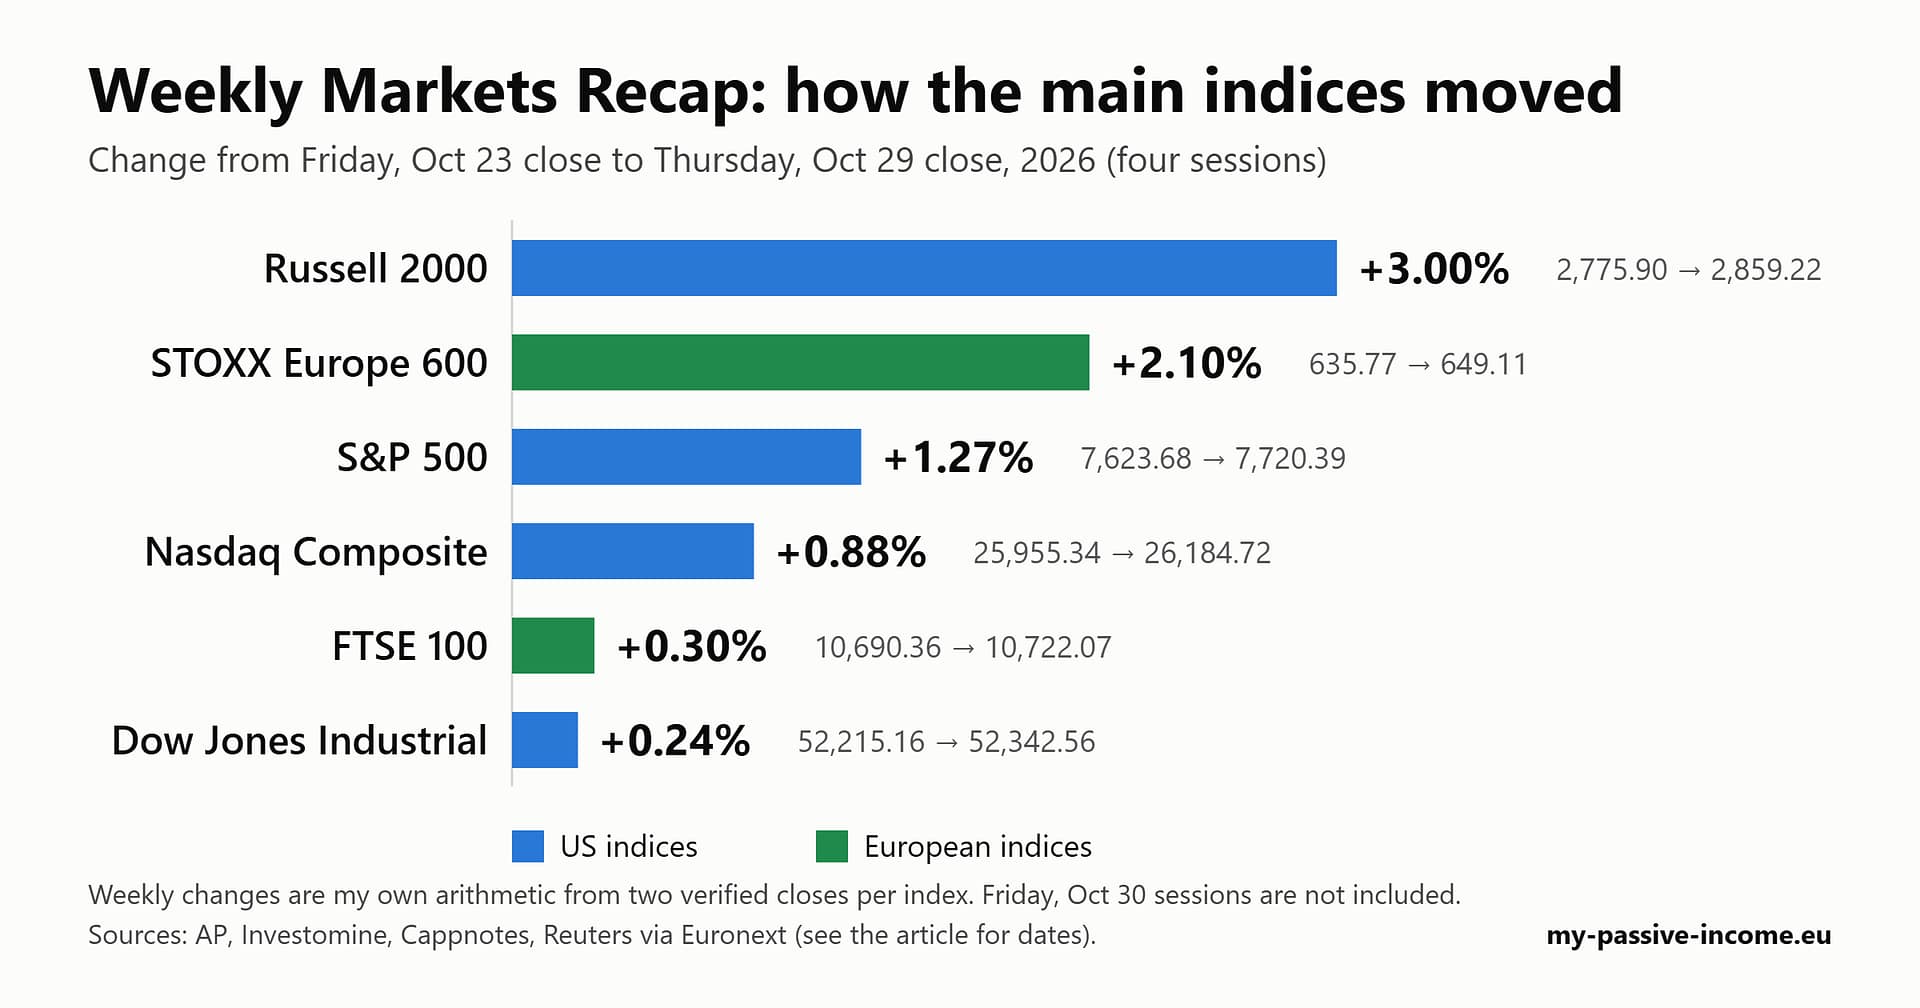
Wall Street’s tech sell-off resumed on Monday, November 2, 2026: the S&P 500 fell 0.51% to 7,541.40 and the Nasdaq Composite lost 1.07% to 25,164.32, while the Dow Jones Industrial Average rose 0.41% to 51,983.98 and European stocks closed higher. Oil dropped about 7.6% on hopes of US-Iran diplomacy. After the close, Apple and Palantir reported and both shares traded lower in after-hours trading. Today, Tuesday, November 3, 2026, the Reserve Bank of Australia has raised rates, Japan is closed for a holiday, Pfizer reports before the US open, JOLTS job openings and factory orders are due at 15:00 UTC, AMD reports after the close and the US midterm elections take place. Data cut-off: 08:30 UTC (10:30 in Bucharest). The freshest source timestamps are Newsquawk (07:13 UTC), XTB (07:42 and 07:00, time zone not stated) and AP (03:53 UTC), so futures, oil and Asian prices may have moved since.
Monday, November 2: how the main indices closed
| Index | Close | Change on the day |
|---|---|---|
| S&P 500 | 7,541.40 | -38.67 points (-0.51%) |
| Dow Jones Industrial Average | 51,983.98 | About +214 points (+0.41%) |
| Nasdaq Composite | 25,164.32 | -272.68 points (-1.07%) |
| Russell 2000 | 2,805.88 | -5.97 points (-0.21%) |
| Nasdaq 100 | About 27,990 | -1.39% (Newsquawk); about 10% below its peak, i.e. in correction (Saxo, XTB) |
| STOXX Europe 600 | 649.44 | +0.4% (Saxo); +0.42% by our arithmetic against Friday’s 646.75 |
| Euro Stoxx 50 | 6,176 to 6,179 | +0.73% to +0.78% (sources differ) |
| DAX | 25,981.09 | +0.63% (Saxo); Newsquawk has +0.64% at 25,983 |
| FTSE 100 | 10,761.33 | +0.29% |
| CAC 40 | 8,047.69 | +0.98% |
| Nikkei 225 (Monday close) | 63,081.64 | -0.33% (our arithmetic against Friday’s 63,290.11) |
Sources: the US closes come from AP via La Nación (published November 2, 2026, 21:32 UTC) and TheStreet (updated 8:27 p.m. EST); the percentage changes also match Yahoo Finance and Stock Titan (S&P 500 -0.51%, Nasdaq -1.07%). The Dow’s point gain differs slightly by source (+213.67 in AP and Yahoo, about +215 in a later Stock Titan update; Newsquawk rounds the level to 51,989), so we show “about +214”. European closes are from the Saxo Asia Market Quick Take (November 3, 2026) and Newsquawk (07:13 UTC), which agree within a few hundredths of a percent; Euro Stoxx 50 and DAX are shown as the two sources give them. The STOXX 600 and Nikkei percentages are our arithmetic against the closes in our previous edition. Market-data summaries, not exchange files, so the last decimal may differ.
Rates, oil, gold and currencies
| Market | Friday (previous edition) | Monday close | This morning |
|---|---|---|---|
| US 10-year Treasury yield | About 4.93% | About 4.89% to 4.91% | n/a |
| US 2-year Treasury yield | About 4.58% to 4.60% | About 4.60% | n/a |
| US 30-year Treasury yield | About 5.31% to 5.33% | About 5.29% | n/a |
| WTI crude (December) | $104.12 | $96.46, down $7.66 (Saxo has $96.33) | About $96.7 (AP, 03:53 UTC) to $97.9 (Investing.com) |
| Brent crude (January) | $113.43 | $104.77 (-7.6%) | About $104.8 (AP, 03:53 UTC) to $105.7 (XTB, 07:00) and $106.5 (Investing.com) |
| Gold (futures) | $3,898.90 (December) | About $3,920 to $3,950; sources disagree on the day’s change | About $3,919 (Investing.com) |
| EUR/USD | About 1.116 | n/a | About 1.1188 (AP) to above 1.12 (Saxo) |
| USD/JPY | n/a | n/a | 157.88 (AP) |
| VIX | 19.42 | 21.15 (+8.9%) | n/a |
Sources: oil settlements from AP (November 3, 2026, 03:53 UTC) (Brent), Newsquawk (WTI) and the Saxo Asia Market Quick Take, which also gives the yields (a single source, so treat them as approximate) and the note that 10- and 30-year yields fell to their lowest since September; VIX and the 10-year snapshot (4.894%, undated) from Yahoo Finance; morning oil and gold from XTB Morning Wrap (7:00, time zone not stated) and Investing.com (November 3, time zone not stated). Gold quotes conflict: Saxo has spot near $3,950 (+0.1%), Yahoo and Investing.com show futures near $3,920 (-1.2% to -1.3%), so we show a range and no daily change. Compare Brent only within the same contract; Friday’s figures are the January contract in our previous edition.
What moved markets on Monday
Tech and chips. Stocks opened higher after Friday’s rout, with the S&P 500 up about 1% at 10:42 a.m. ET before turning lower around 3:04 p.m. ET (Stock Titan). Per Newsquawk, technology fell 2.66% and energy 3.97% while consumer discretionary rose 2.25%; AP says nearly seven in ten S&P 500 stocks rose, and Nvidia ended down 1.3% after an early 2.6% gain. XTB says a key semiconductor index has lost a cumulative 12% over three sessions. Oracle fell about 8.8%: Yahoo Finance reports a $20 billion capital raise (about $10 billion in bonds and $10 billion in stock), and Newsquawk adds that a $10 billion share offering was reportedly priced at $116, about 11% below Friday’s close. TheStreet reports that Marvell agreed to buy Lumentum in a deal it values at $115 billion; Stock Titan has Lumentum down 18.6% and Marvell down 12.7%. We have not confirmed the deal terms with the companies.
Winners and the Dow. IDEXX Laboratories rose 21.85% after raising its 2026 forecast, Sherwin-Williams (+5.6%) and Home Depot (+3.3%) helped the Dow, and airlines gained as oil fell (United +4.8%), all per Stock Titan.
Data. The ISM manufacturing index rose to 55.5 for October against a 54.5 forecast, and September construction spending fell 1.9% against an expected rise (Stock Titan, Saxo); AP adds that price increases slowed.
Oil and Iran. Brent fell 7.6% to $104.77 on hopes that the US and Iran would resume diplomacy, with Stock Titan citing reports that Iran’s supreme leader gave the government some authority to hold talks. Overnight, XTB, Newsquawk and Yahoo Finance report that the Wall Street Journal said the US carried out a limited strike on Iran’s Qeshm Island; XTB adds that Iran’s Revolutionary Guards claim to have captured two US drones and shot down a third, a claim we could not verify, and that President Trump expressed optimism about a deal while mediators work to narrow differences. Oil was contained overnight. These are press reports of an unresolved situation and could reverse quickly.
After the close: Apple and Palantir
Apple reported fiscal fourth-quarter results (Apple press release, November 2, 2026): revenue of $114.5 billion, up 12% from a year earlier, and diluted EPS of $2.10, up 14%, of which tariff refunds added $0.05. Gross margin was 47.9%, including about one percentage point from those refunds. Full-year revenue was a record $479 billion, and the quarterly dividend is $0.27 per share, payable November 16. Analysts had expected about $2.00 and $113.4 billion to $113.5 billion (Yahoo, TheStreet). The press release contains no guidance; according to Investing.com and Stock Titan, the company forecast lower gross margins for the holiday quarter on memory-chip costs and services growth below expectations. Apple fell 1.83% in the regular session and was down about 1% to 2.8% after hours depending on source and time; we have not read the earnings-call transcript.
Palantir (press summaries, not the company release): third-quarter revenue of $2.31 billion, up 96%, against $2.17 billion to $2.18 billion expected, and adjusted EPS of $0.44 against $0.40 to $0.41, with full-year revenue guidance raised (Yahoo Finance, Newsquawk). Shares were down about 3% to 4.8% after hours.
Overnight in Asia and Europe’s open
The Reserve Bank of Australia raised its cash rate by 25 basis points to 4.85%, the highest since 2008 and its fifth hike this year, in a 6-3 vote (Investing.com, XTB); Newsquawk says it did not signal a December hike. We have not read the RBA’s own statement. Japan was closed for a holiday. Mid-session readings from AP (03:53 UTC) had the Kospi down 2.5% to 5,712.57, the Hang Seng up 0.3% to 23,469.64, the Shanghai Composite down 0.7% to 3,614.17 and Australia’s ASX 200 up 0.2% to 8,871.80; the Saxo Asia Market Quick Take later had the Kospi at -3.3% (5,666) and the ASX near +0.4%, and Investing.com had the Kospi down as much as 3.6%, so the Korean move is shown as a range of roughly 2.5% to 3.6%. These are not final closes. Saxo and Newsquawk cite Chinese market-support measures, including eased buyback rules and a third round of a People’s Bank of China swap facility, while the PBoC set the yuan midpoint at 6.7150 and raised the FX reserve requirement ratio. South Korean October CPI was 2.8% against 2.9% expected (Newsquawk).
US futures were lower this morning: about -0.5% for the S&P 500 and Nasdaq 100 at 07:00 (XTB, time zone not stated), but only about -0.15% in an undated Investing.com ticker. In Europe, Newsquawk lists this morning’s company results: Bayer raised its 2026 adjusted EBITDA guidance (third-quarter adjusted EBITDA EUR 1.62 billion against EUR 1.42 billion expected; shares indicated +2.7%), Lufthansa cut its 2026 adjusted EBIT guidance to EUR 1.7 to 2.0 billion, Hugo Boss cut its guidance (indicated -2.6%), Philips reiterated its outlook (indicated +2.8%) and Fresenius Medical Care narrowed its outlook (indicated -2.8%).
Tuesday, November 3: what is scheduled
| Time (UTC / Bucharest / ET) | Event | Consensus | Previous / result |
|---|---|---|---|
| Already out | Reserve Bank of Australia decision | 25 bp hike expected (AP) | Raised to 4.85% (6-3 vote) |
| Already out | South Korea CPI, October | 2.9% | 2.8% |
| 07:30 / 09:30 / 02:30 | Swiss CPI, October, year on year | 1.2% | Previous 1.0%; actual not found |
| 10:00 / 12:00 / 05:00 | UK 10-year gilt auction | n/a | Previous yield 5.418%, bid-to-cover 3.61 |
| 10:30 / 12:30 / 05:30 | German 5-year government bond auction | n/a | Previous yield 3.22%, bid-to-cover 1.1 |
| 11:45 / 13:45 / 06:45 (XTB; before the open) | Pfizer Q3 results, adjusted EPS / revenue | About $0.73 / $15.9 billion (TIKR, Oct 26) | $0.87 year-ago EPS; a $650 million (about $0.10 a share) Innovent charge was flagged |
| Before the open | Shopify Q3 results | Not found | n/a |
| 15:00 / 17:00 / 10:00 | US JOLTS job openings, September | 7.164 million | Previous 7.079 million |
| 15:00 / 17:00 / 10:00 | US factory orders, September (m/m); revised durable goods and core | +1.2%; +1.8% and +0.5% | Previous +0.1%; +1.8% and +0.5% |
| Through the day | Central bank speakers: ECB’s Moulin (10:00 and 14:00 UTC), Nagel (17:00), Sleijpen (18:15) and Bank of Canada’s Macklem (16:00) | n/a | XTB lists no Federal Reserve speakers |
| After the close | AMD Q3 results, EPS / revenue | $1.42 / about $13.06 billion (Hudson Labs, Oct 7) | Company guidance about $13.0 billion plus or minus $0.3 billion, gross margin about 56%; report time not found |
| After the close | Arista Networks, Amgen, Booking Holdings results | Not found | n/a |
| Evening and overnight | US midterm elections; first results expected overnight, starting with Indiana and Kentucky | n/a | n/a |
Sources: times and the macro consensus figures are from the XTB economic calendar (November 3, 2026, 07:42, event times in GMT); the Pfizer consensus is from TIKR (October 26, 2026) and the AMD consensus and guidance from Hudson Labs (October 7, 2026), so both may have changed; the AMD consensus is shown as Hudson Labs states it and we did not confirm whether it is a GAAP or adjusted figure. Bucharest times assume UTC+2 and ET assumes UTC-5. Report times for companies other than Pfizer are not confirmed with the companies.
The next trading days
According to the Saxo Asia Market Quick Take (November 3, 2026): on Wednesday, November 4, the US Treasury’s quarterly refunding announcement and earnings from Qualcomm, Novo Nordisk, Uber, McDonald’s and Arm; on Thursday, November 5, the Bank of England decision, where Saxo expects a hike (a forecast, not a decision), and earnings from Toyota, Sony and Airbnb; and on Friday, November 6, US October payrolls, with consensus of about 55,000 to 65,000 jobs depending on the source. See our McDonald’s Q3 2026 earnings preview for November 4 and our weekly markets recap for last week’s context.
Sources
- Apple: fourth-quarter fiscal 2026 results (press release, November 2, 2026)
- Market-data summaries and news, not primary sources: AP via La Nación (November 2, 2026, 21:32 UTC); TheStreet (November 2, 2026); Stock Titan live blog (November 2, 2026); Yahoo Finance live blog (November 2, 2026); Newsquawk European equity opening news (November 3, 2026, 07:13 UTC); Saxo Asia Market Quick Take (November 3, 2026; the page metadata is inconsistent, but its figures match AP and Newsquawk); AP via WRAL (November 3, 2026, 03:53 UTC); Yahoo Finance Asia report (November 3, 2026); Investing.com Asia report (November 3, 2026); XTB Morning Wrap (November 3, 2026, 7:00); XTB economic calendar (November 3, 2026, 07:42); TIKR Pfizer preview (October 26, 2026); Hudson Labs AMD preview (October 7, 2026). All pages were read on November 3, 2026, between 08:27 and 08:34 UTC.
Get new articles by email
Ex-dividend dates, earnings previews and P2P platform changes, straight to your inbox. Unsubscribe anytime.
Disclaimer: This article is for informational purposes only and does not constitute investment advice. Figures come from the sources listed, as of the times stated, and may be revised. Market-data summaries can differ slightly from official exchange figures. Confirm current prices with your broker. Investing involves risk, including the possible loss of capital.