Stocks are heading for a weekly gain even after Thursday’s technology selloff. From last Friday’s close to Thursday’s close, the Russell 2000 rose 3.00%, the STOXX Europe 600 2.10%, the S&P 500 1.27%, the Nasdaq Composite 0.88%, the FTSE 100 0.30% and the Dow Jones Industrial Average 0.24% (my arithmetic from the closes below). This recap was written on Friday, October 30, 2026, before Friday’s US and European sessions had closed, so the weekly figures cover the four sessions from Monday to Thursday and Friday’s moves are shown separately as provisional readings. The freshest source below is Saxo’s quick take, as of about 05:00 CET.
How the main indices did: October 23 close to October 29 close
| Index | Close, Fri Oct 23 | Close, Thu Oct 29 | Change (my arithmetic) |
|---|---|---|---|
| S&P 500 | 7,623.68 | 7,720.39 | +1.27% |
| Nasdaq Composite | 25,955.34 | 26,184.72 | +0.88% |
| Dow Jones Industrial Average | 52,215.16 | 52,342.56 | +0.24% |
| Russell 2000 | 2,775.90 | 2,859.22 | +3.00% |
| STOXX Europe 600 | 635.77 | 649.11 | +2.10% |
| FTSE 100 | 10,690.36 | 10,722.07 | +0.30% |
Sources: the US closes for October 23 are in AP via La Nacion (October 23, 2026, 23:35) and Investomine (report dated October 23, published October 25); those for October 29 are in AP via myMotherLode (October 29, 2026, 4:11 p.m.) and Cappnotes (page last modified October 29, 2026, 21:34 UTC), with TradingKey (October 30, 2026, 12:44 a.m., time zone not stated) matching the S&P 500 and Nasdaq. The STOXX 600 and FTSE 100 closes for October 23 are from Investomine and Cappnotes; the October 29 STOXX 600 close is in Cappnotes and Reuters via Euronext (October 29, 2026, 19:01), and the October 29 FTSE 100 level is from Cappnotes alone, with Saxo (October 30, about 05:00 CET) confirming the +0.3% move. I left out the DAX: last Friday’s sources mix a price index (25,152.30, Cappnotes) with a total-return index (25,181.65, Investomine), and Thursday’s close is 26,039.68 (Cappnotes) or 26,052.75 (Deutsche Börse figure via ad-hoc-news.de, 17:59 CET), so no like-for-like weekly figure is reliable (roughly +3.5% on the price index). These are market-data summaries, not exchange files.
Rates, oil and gold
| Market | Fri Oct 23 | Thu Oct 29 | Change (my arithmetic) |
|---|---|---|---|
| US 10-year Treasury yield | 4.999% | 4.98% | About -2 bp |
| US 2-year Treasury yield | 4.686% | 4.61% | About -8 bp |
| US 30-year Treasury yield | 5.33% | 5.32% | About -1 bp |
| Brent crude (December contract) | $116.72 | $114.88 | -1.58% |
| WTI crude (December contract) | $103.27 | $102.00 | -1.23% |
| Gold (December futures) | About $4,008 | $4,031.70 | About +0.6% |
Sources: October 23 from Investomine (yields, Brent, WTI and gold) and Cappnotes; October 29 from Cappnotes, a single source for Thursday’s yields and settlements. The gold change is approximate (Friday’s level is given as “about”), and yield changes are rounded. The 10-year yield closed at 5.044% on Wednesday, the highest of the week’s closes in the data I found (our October 29 edition).
Day by day
| Day | S&P 500 close (change) | Nasdaq Composite close (change) | Brent, December settlement |
|---|---|---|---|
| Mon, Oct 26 | 7,676.77 (+0.70%) | 26,169.38 (+0.82%) | $115.81 |
| Tue, Oct 27 | 7,722.60 (+0.60%) | 26,477.81 (+1.18%) | $113.88 |
| Wed, Oct 28 | 7,743.98 (+0.28%) | 26,549.85 (+0.27%) | $115.32 |
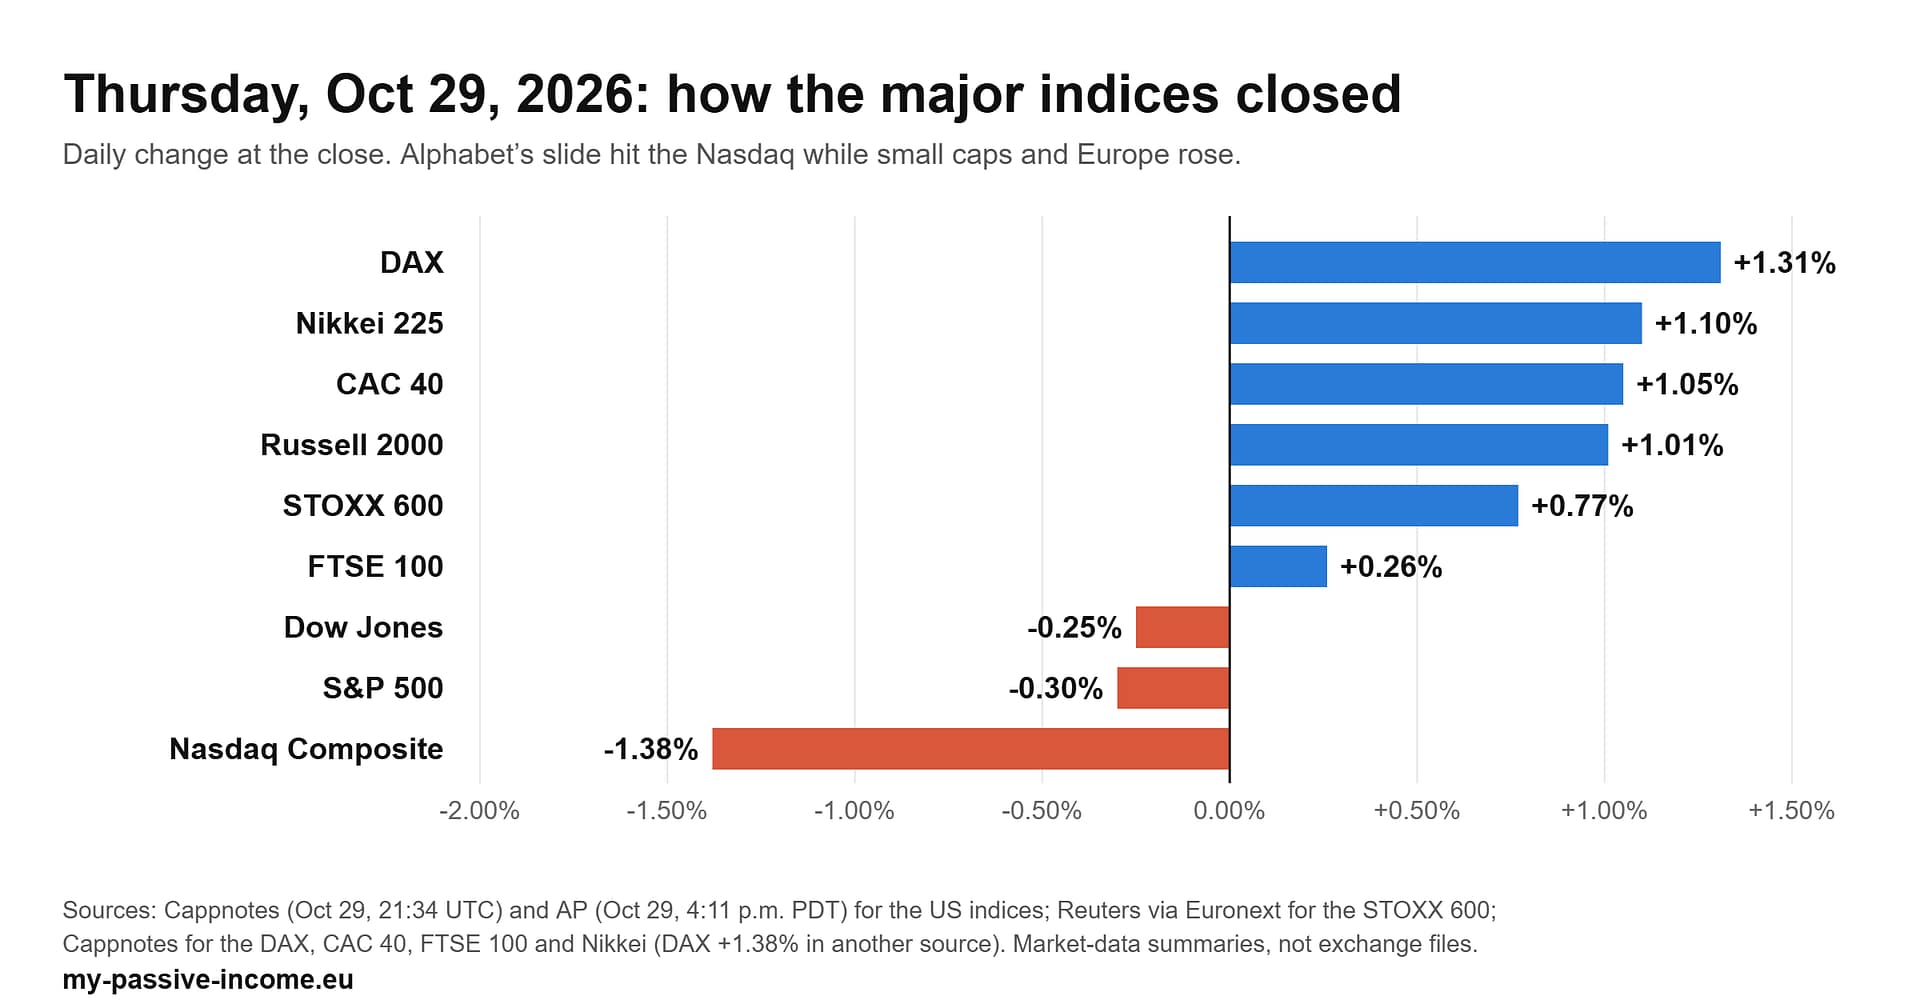
| Thu, Oct 29 | 7,720.39 (-0.30%) | 26,184.72 (-1.38%) | $114.88 |
Sources: Cappnotes daily closing notes, cross-checked in our daily editions of October 27, October 28, October 29 and October 30. Chips led Monday to Wednesday, then the Philadelphia Semiconductor Index fell 1.42% on Thursday (TradingKey; Cappnotes).
The five events that mattered
1. The Fed held, with two votes for a hike. On Wednesday, October 28 the Federal Open Market Committee left the target range at 3-3/4 to 4 percent in a 10-2 vote; Governor Lisa Cook and Cleveland Fed President Beth Hammack preferred a quarter-point increase (Federal Reserve statement, October 28). Markets priced roughly a 78% chance of a December hike, down from about 84% before the decision (CME FedWatch, reported in our October 29 edition); that is market pricing, not a forecast by this site. The next meeting is December 8-9 (Fed calendar).
2. Big Tech earnings reopened the AI-spending debate. Alphabet fell 12.64% on Thursday, its worst day since listing, after results that missed estimates and capital spending guidance of $195 billion to $205 billion for 2026; Microsoft reported revenue of $92.28 billion against a $90.69 billion estimate, with Azure up 48% (Cappnotes; TradingKey; I have not seen either company’s release). After Thursday’s close Amazon reported net sales of $201.9 billion (up 12%), operating income of $28.1 billion (from $17.4 billion), diluted earnings of $1.89 per share (from $1.95, with the year-ago figure including $9.5 billion of pre-tax gains on Anthropic investments) and AWS sales of $46.0 billion (up 39%); it expects 2026 cash capital spending of about $220 billion, and trailing-twelve-month free cash flow was an outflow of $42.4 billion (Amazon release, SEC exhibit 99.1, October 29). Amazon fell about 7% and Intel about 23% after hours (Saxo); Cappnotes put Intel’s fall at 17%, so the size depends on the time of the quote.
3. Strong growth, hot inflation. US third-quarter GDP grew at an annualised 3.4% against 2.2% in the second quarter (TradingKey; I have not seen the BEA release). The Bureau of Economic Analysis shows the September PCE price index up 0.5% on the month and 3.6% on the year, with core PCE up 0.3% and 3.1% (BEA, October 29, 8:30 a.m. EDT). Treasuries rallied anyway, taking the 10-year yield to 4.98% (Cappnotes).
4. The ECB and Bank of Japan paused. The ECB left rates unchanged on Thursday but signalled a possible hike in December, and President Christine Lagarde announced she will step down; the STOXX 600 closed at its highest level since September 8 (Reuters via Euronext, October 29, 19:01). On Friday the Bank of Japan kept its guideline at around 1.25% in an 8-1 vote, with Hajime Takata proposing 1.5% (Bank of Japan, October 30).
5. Oil stayed near $115 on Gulf headlines. Brent’s December contract ended the four sessions 1.58% lower, but it swung between $113.88 and $115.81 as press reports described Houthi attacks on Saudi targets, mediation around Iran and a tanker incident near the Strait of Hormuz; I have not confirmed them and accounts conflict (Cappnotes; Saxo). Brent was on course for a monthly gain of nearly 11% in October (FinanceFeeds, October 30, 06:55 UTC), and the December contract expires today, so from Monday quotes will refer to the cheaper January contract. Also: Brazil’s Ibovespa fell 13.88% on Monday after Lula’s re-election, and Binance estimated a $6.3 billion theft (press reports).
Friday so far (not in the weekly figures)
Early readings point to a weaker end to the week for technology. Nasdaq 100 futures were down about 1.9% in early Asian trading, the Nikkei fell more than 2% and the Kospi more than 3% in the morning (Saxo Morning Brew, October 30). Brent was near $116.50, gold near $3,970 and the 10-year yield about 4.92% (Saxo quick take, about 05:00 CET). These are early quotes taken at different times; Friday’s US and European closes will change the weekly numbers above.
Next week: the calendar
| Day | Data and central banks | Earnings |
|---|---|---|
| Mon, Nov 2 | US ISM manufacturing PMI | Apple, Palantir, Vertex, Marriott, Estée Lauder |
| Tue, Nov 3 | Reserve Bank of Australia decision; US midterm elections | AMD, Amgen, Arista, Pfizer, Eaton |
| Wed, Nov 4 | US ADP employment, ISM services PMI | Novo Nordisk, Toyota, Qualcomm, Arm, McDonald’s, Uber |
| Thu, Nov 5 | Bank of England decision; US jobless claims | Sony, ConocoPhillips, Cloudflare |
| Fri, Nov 6 | US nonfarm payrolls and unemployment rate; euro-area retail sales | Moderna, Humana, Enbridge |
Source: Saxo Morning Brew (October 30, 2026). I have not confirmed the company dates with the companies, so check each investor-relations page. We have already published previews of Pfizer and McDonald’s. The next Fed decision is not until December 9.
Sources
- Federal Reserve: FOMC statement (October 28, 2026)
- Federal Reserve: FOMC meeting calendar
- Bureau of Economic Analysis: Personal Income and Outlays, September 2026 (October 29, 2026)
- Bank of Japan: monetary policy decision (October 30, 2026)
- Amazon: third quarter 2026 results, SEC exhibit 99.1 (October 29, 2026)
- Market-data summaries and news, not primary sources: AP via La Nacion (October 23, 2026, 23:35); AP via myMotherLode (October 29, 2026, 4:11 p.m.); Investomine weekly market report (dated October 23, published October 25, 2026); Cappnotes (page last modified October 29, 2026, 21:34 UTC); Reuters via Euronext (October 29, 2026, 19:01); TradingKey (October 30, 2026, 12:44 a.m., time zone not stated); ad-hoc-news.de (DAX close, October 29, 2026, 17:59 CET); Saxo Market Quick Take (October 30, 2026, levels as of about 05:00 CET); Saxo Morning Brew (October 30, 2026); FinanceFeeds (October 30, 2026, 06:55 UTC). Daily closes for Monday to Wednesday come from our own daily editions, which cite Cappnotes, TheStreet and AP.
Get new articles by email
Ex-dividend dates, earnings previews and P2P platform changes, straight to your inbox. Unsubscribe anytime.
Disclaimer: This article is for informational purposes only and does not constitute investment advice. Figures come from the sources listed, as of the times stated, and may be revised. Market-data summaries can differ slightly from official exchange figures. Confirm current prices with your broker. Investing involves risk, including the possible loss of capital.