Mondelez International (Nasdaq: MDLZ), the maker of Oreo, Cadbury and Toblerone, reports third-quarter 2026 results on Thursday, October 29, 2026. The company will release them at 4:05 p.m. Eastern (21:05 Central European Time, because US clocks change a few days after Europe’s), with a listen-only webcast at 5:00 p.m. Eastern. This preview lines up the last four quarters against the same quarters a year earlier, works out what full-year guidance implies for the second half, and covers analyst consensus, the dividend and what to watch.
The recent quarters, each against the same quarter a year earlier
| Metric | Q3 2025 (vs Q3 2024) | Q4 2025 (vs Q4 2024) | Q1 2026 (vs Q1 2025) | Q2 2026 (vs Q2 2025) |
|---|---|---|---|---|
| Net revenues | $9,744 million (+5.9% from $9,204 million) | $10,496 million (+9.3% from $9,604 million) | $10,080 million (+8.2% from $9,313 million) | $9,355 million (+4.1% from $8,984 million) |
| Organic net revenue growth (volume/mix, pricing) | +3.4% (-4.6 points, +8.0 points) | +5.1% (-4.8 points, +9.9 points) | +3.0% (-0.5 points, +3.5 points) | +2.2% (+0.7 points, +1.5 points) |
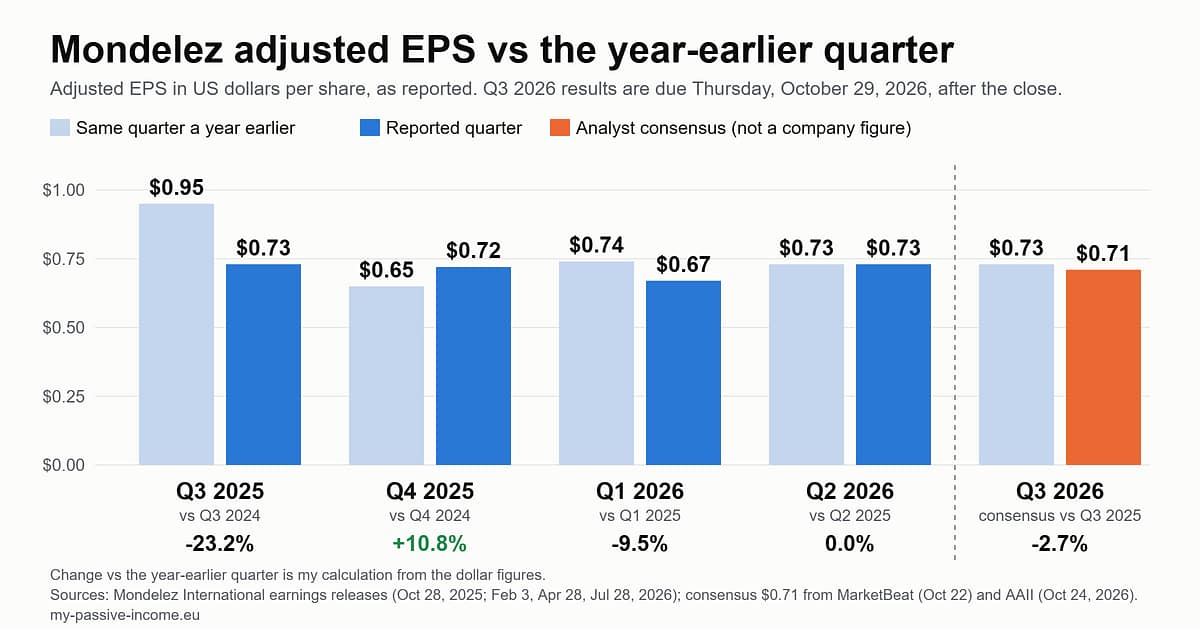
| Adjusted EPS (as reported) | $0.73 (from $0.95: -23.2%) | $0.72 (from $0.65: +10.8%) | $0.67 (from $0.74: -9.5%) | $0.73 (from $0.73: 0.0%) |
| GAAP diluted EPS | $0.57 (from $0.63) | $0.51 (from $1.30) | $0.44 (from $0.31) | $1.20 (from $0.49) |
| Adjusted operating income | $1,171 million (-32.6% from $1,738 million) | $1,246 million (+30.1% from $958 million) | $1,182 million (-14.0% from $1,374 million) | $1,222 million (-4.8% from $1,283 million) |
| Adjusted operating margin (my calculation) | 12.0% (from 18.9%) | 11.9% (from 10.0%) | 11.7% (from 14.8%) | 13.1% (from 14.3%) |
Sources: the four Mondelez earnings releases listed under Sources (Q3 2025 on October 28, 2025; Q4 and full-year 2025 on February 3, 2026; Q1 2026 on April 28, 2026; Q2 2026 on July 28, 2026). Percentage changes and margins are my calculations from the dollar figures unless a release prints them, so they can differ by a tenth of a point from the company’s. The four 2025 quarterly revenues add up to the company’s full-year 2025 net revenues of $38,537 million, and the four adjusted EPS figures to its $2.92. Adjusted EPS excludes items the company reconciles in each release; GAAP EPS moves more, and the Q2 2026 figure of $1.20 includes items that adjusted EPS leaves out.
Two things stand out. The Q3 2025 comparison base is low: adjusted operating income fell by about a third that quarter and the margin was 12.0%, against 13.1% in Q2 2026. And the source of growth has shifted: in Q3 and Q4 2025, price increases of 8.0 and 9.9 points were partly offset by volume/mix declines of 4.6 and 4.8 points, while in Q2 2026 pricing added 1.5 points and volume/mix added 0.7 points.
Organic growth by region
| Organic net revenue growth | Q3 2025 | Q4 2025 | Q1 2026 | Q2 2026 |
|---|---|---|---|---|
| Latin America | +4.7% | +4.4% | +5.1% | +8.4% |
| Asia, Middle East and Africa | +5.3% | +7.5% | +11.3% | +7.1% |
| Europe | +5.1% | +8.3% | -0.6% | -3.5% |
| North America | -0.3% | -0.5% | +0.5% | +3.4% |
Each column compares the quarter with the same quarter a year earlier. Europe, the largest region at $3,377 million of Q2 2026 net revenues, is the one to watch: its organic growth went from +8.3% in Q4 2025 to -3.5% in Q2 2026 against a Q3 2025 base of +5.1%. Source: the company releases listed under Sources.
Full-year guidance: three updates
| Metric (full year 2026) | February 3, 2026 | April 28, 2026 | July 28, 2026 |
|---|---|---|---|
| Organic net revenue growth | Flat to 2% | Flat to 2% (reaffirmed) | At least 2% (raised from flat to 2%) |
| Adjusted EPS growth, constant currency | Flat to 5% | Flat to 5% | Flat to 5% (maintained) |
| Free cash flow | About $3 billion | About $3 billion | About $3 billion |
| Currency effect included | About +2.0% on net revenues and about +$0.06 on adjusted EPS | About +2.0% and about +$0.06 | About +2.0% and about +$0.05 |
Sources: the Mondelez releases of February 3, April 28 and July 28, 2026. The company said the July change to organic growth reflects year-to-date performance. The outlook does not reflect potential tariff changes to USMCA-compliant trade, and the company describes greater than usual volatility from geopolitics, trade, regulation and commodity prices. Cocoa is named in the release only in the standard list of risks; in the February release the CEO said 2025 profitability had been hit by cocoa costs and pointed to stabilizing cocoa costs as part of the 2026 plan.
What the guidance implies for the second half (my calculation)
| Adjusted EPS | Amount | Note |
|---|---|---|
| Full-year 2025 | $2.92 | Company figure; second half 2025 = $0.73 + $0.72 = $1.45 |
| First half 2026, constant currency | About $1.34 | $0.63 in Q1 plus $0.71 in Q2, against $1.47 in the first half of 2025 (-8.8%, which matches the company’s six-month figure) |
| Guidance: flat to +5% on $2.92, constant currency | $2.92 to $3.07 | Constant-currency basis; reported figures would include the currency effect |
| Implied second half 2026, constant currency | About $1.58 to $1.73 | Guidance range minus the first half |
| Implied growth on second half 2025 ($1.45) | About +9% to +19% | Rounded; the company’s quarterly constant-currency figures are rounded, so treat this as approximate |
In other words, guidance needs a second half that is clearly better than the first, which fell 8.8% from a year earlier on the same constant-currency basis. The company does not publish a second-half forecast; this is my arithmetic from its figures, and a move in cocoa, pricing or currency would change it.
What analysts expect, and the share price
This section uses third-party data, which is not from the company; each figure carries its source and date. Consensus is for the same quarter, compared with the same quarter a year earlier.
| Metric | Consensus | Year-earlier actual (company) | Change |
|---|---|---|---|
| Q3 2026 adjusted EPS | $0.71 (MarketBeat, October 22, 2026: $0.711; AAII, October 24: $0.71 from 17 analysts; Barchart, October 8: $0.71) | $0.73 (Q3 2025) | About -2.7% |
| Q3 2026 net revenues | $9.98 billion (MarketBeat, October 22, 2026) | $9,744 million (Q3 2025) | About +2.4% (my calculation) |
| Full-year 2026 adjusted EPS | $3.05 (Barchart, October 8, 2026) | $2.92 (2025) | About +4.5% |
The company beat the EPS consensus in each of the previous four quarters, according to Barchart (October 8, 2026); in Q2 it reported $0.73 against $0.68 and revenue of $9.36 billion against $9.21 billion (MarketBeat, October 22, 2026). RBC Capital said on October 26, 2026 that it is roughly in line with consensus on revenue and slightly below it on EPS, citing its view of second-half phasing, while seeing full-year guidance as achievable (Investing.com).
One more calculation, using figures from different sources and dates, so it is approximate: the first-half adjusted EPS of $1.40 plus the $0.71 Q3 consensus leaves about $0.94 for the fourth quarter to reach the $3.05 full-year consensus, against $0.72 in Q4 2025 (roughly +31%). If that is how analysts see it, much of the full-year expectation rests on Q4, which is one reason the guidance comments on October 29 matter.
MDLZ closed at $62.97 on Monday, October 26, 2026 (Nasdaq close as reported by ad-hoc-news, October 27); the 52-week range was $51.20 to $66.65 (Yahoo Finance, October 23, 2026). MarketBeat (October 22, 2026) listed a "Moderate Buy" consensus of 17 buy and 10 hold ratings with an average price target of $68.86; these are third-party opinions, not company data. Using the closing price (my calculation):
| Measure | Value |
|---|---|
| Share price (close, Oct 26, 2026) | $62.97 |
| Price to 2025 adjusted EPS of $2.92 | about 21.6x |
| Price to 2026 consensus EPS of $3.05 | about 20.6x |
| Quarterly dividend of $0.52, $2.08 a year | yield about 3.3% on the price above |
| Annual dividend as a share of 2025 adjusted EPS | about 71% |
| Annual dividend as a share of 2026 consensus EPS | about 68% |
Price and consensus move daily, so check both with your broker before the release.
What to watch on October 29
- Net revenues against $9,744 million in Q3 2025, and the $9.98 billion consensus. Organic growth has slowed from +5.1% in Q4 2025 to +2.2% in Q2 2026; the Q3 2025 base was +3.4%.
- Adjusted EPS against $0.73 a year earlier and the $0.71 consensus, and the adjusted operating margin against 12.0% in Q3 2025 and 13.1% in Q2 2026.
- Pricing against volume. Pricing added 8.0 points in Q3 2025 and 1.5 points in Q2 2026; volume/mix moved from -4.6 points to +0.7 points over the same stretch.
- Europe. Organic growth was -0.6% in Q1 and -3.5% in Q2 2026 against +5.1% in Q3 2025.
- Guidance. Whether the "at least 2%" organic outlook and the flat-to-5% constant-currency EPS range change, and what the company says about cocoa and the fourth quarter.
- Cash flow. First-half free cash flow was $668 million (operating cash flow of $1,322 million less $654 million of capital spending), against $818 million a year earlier, and the outlook is about $3 billion for the year.
The dividend
Mondelez pays a quarterly dividend of $0.52 per share ($2.08 a year), after a 4% increase announced with the Q2 results on July 28, 2026 from $0.50. The most recent payment was declared on August 13, 2026 (record date September 30, paid October 14, 2026); the one before was $0.50, declared on May 20 (record date June 30, paid July 14). MarketBeat lists September 30 as the ex-dividend date; under the US one-day settlement cycle the ex-date falls on the record date. I found no announcement of the next dividend yet, so buying shares now does not earn the October payment. Last year the company declared its fourth-quarter dividend on December 11, 2025 ($0.50, record date December 31, paid January 14, 2026); a similar timetable this year is my expectation, not something the company has confirmed.
In the first half of 2026 the company paid $1,287 million in dividends and repurchased $212 million of shares (against $1,653 million of repurchases in the first half of 2025). Dividends paid were therefore larger than first-half free cash flow of $668 million, so the full-year cash flow outlook is the figure to compare against the dividend bill.
For investors in Europe
- MDLZ pays in U.S. dollars, and U.S. withholding tax applies by default; the rate for non-U.S. investors depends on your broker having a valid Form W-8BEN. See our W-8BEN guide.
- The results arrive at 21:05 Central European Time on Thursday, after European markets have closed, so the first reaction will be in US after-hours trading and in Friday’s session.
- The dollar and euro exchange rate moves the euro value of the dividend independently of anything Mondelez reports.
Sources
- Mondelez: announcement of the Q3 2026 results date, release and webcast times (GlobeNewswire, October 15, 2026), via Finviz
- Mondelez: Q3 2025 results, Form 8-K exhibit (October 28, 2025)
- Mondelez: Q4 and full-year 2025 results and 2026 outlook, Form 8-K exhibit (February 3, 2026)
- Mondelez: Q1 2026 results, Form 8-K exhibit (April 28, 2026)
- Mondelez: Q2 2026 results and updated outlook, Form 8-K exhibit (July 28, 2026)
- Mondelez: $0.52 quarterly dividend declaration (August 13, 2026)
- Mondelez: $0.50 quarterly dividend declaration (May 20, 2026)
- Mondelez: $0.50 quarterly dividend declaration (December 11, 2025)
- Third-party data (consensus, price and analyst ratings), not from the company: MarketBeat (October 22, 2026); MarketBeat via Defense World (October 22, 2026); AAII (October 24, 2026); Barchart via Yahoo Finance (October 8, 2026); Yahoo Finance quote page (October 23, 2026 close); ad-hoc-news (October 27, 2026); Investing.com on RBC Capital (October 26, 2026)
Get new articles by email
Ex-dividend dates, earnings previews and P2P platform changes, straight to your inbox. Unsubscribe anytime.
Disclaimer: This article is for informational purposes only and does not constitute investment advice. Company figures are taken from the releases listed; consensus, the share price and analyst ratings come from the third-party sources listed, as of the dates stated; and the second-half, fourth-quarter, percentage-change, margin and valuation figures are my own arithmetic, not a company forecast. Confirm current figures with your broker or the company’s investor relations page. Investing involves risk, including the possible loss of capital, and a dividend payment is never guaranteed.