PepsiCo reported third-quarter 2026 results on Thursday, October 8, 2026, and the report was two stories at once. Revenue and core earnings per share beat expectations, and the shares rose 3.7% to $128.34. But the company also lowered its full-year profit forecast, because North America is still weak. Here is what the numbers say, in the order that matters for a dividend investor. If you want the setup before the report, read our earnings preview.
The quarter in numbers
The quarter covers the 12 weeks ended September 5, 2026. Figures are from PepsiCo’s own results.
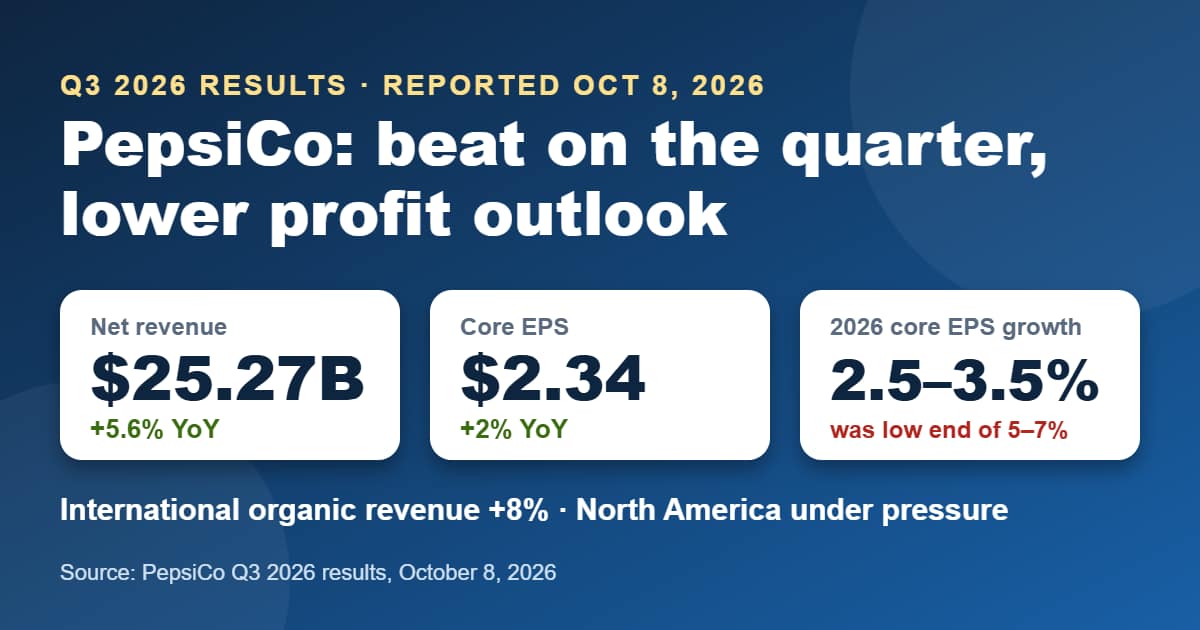
- Net revenue: $25.27 billion, up 5.6% from $23.94 billion, ahead of the roughly $25.0 billion analysts expected. Organic growth (without currency and acquisitions) was 3.1%, the fastest since the fourth quarter of 2023; acquisitions added 1.7 points and currency 0.7 points.
- Core EPS: $2.34, up 2% from $2.29 and above the roughly $2.30 expected. Core EPS excludes items PepsiCo treats as one-off.
- Reported (GAAP) EPS: $2.23, up 17% from $1.90. Net income attributable to PepsiCo was $3.05 billion, against $2.60 billion a year earlier.
- Core operating margin: 16.9%, down 35 basis points from 17.3%. The quarter included $178 million of tariff refunds that helped core operating profit.
- Volumes: global beverage volume rose 3%. The CFO said global food volume rose 1%, or 4% excluding the grains business in South Africa.
Two speeds: international up, North America behind
The growth came from outside the United States. International organic revenue grew 8%, the 22nd consecutive quarter of at least mid-single-digit organic growth, and the international core operating margin improved by 105 basis points. The CEO said international accounts for 45% of PepsiCo’s profit year to date. Third-party summaries of the report put Asia-Pacific food volume up about 11%.
North America is the opposite. Core operating margin fell 280 basis points at the foods business (Frito-Lay and Quaker) and 15 basis points at the beverage business. Beverage volume in North America declined; Zacks reports a 2% drop, and the CEO said on the call: “We do not feel good about the beverage business.” Food volume in North America rose, helped by U.S. salty snacks, and management described the year so far as low-single-digit positive volume growth after a decline last year. That recovery follows the price cuts of up to 15% on Lay’s, Doritos and Cheetos announced in February 2026. Since then PepsiCo has said it will raise prices on some items again, while promising that next year’s prices will stay below 2025 levels for most take-home formats, according to the call transcript.
The forecast was lowered
This is the part that kept the beat from being a clean one. PepsiCo now expects 2026 core EPS to grow 2.5% to 3.5%. It had previously guided to the low end of 5% to 7%. Core EPS growth at constant currency is now 1% to 2%, down from the low end of 4% to 6%.
The revenue outlook moved the other way: organic revenue growth of about 3% (previously 2% to 4%) and net revenue growth of about 6% (previously 4% to 6%), helped by currency and acquisitions. Management also expects continued margin pressure in North America in the fourth quarter. The cash-return plan was unchanged: $8.9 billion for 2026, made up of $7.9 billion in dividends and $1.0 billion in share repurchases. Capital spending is still expected below 5% of net revenue and free cash flow conversion at least 80%.
What management is doing about it
- Marketing: a partnership with the agency Publicis aimed at using more data to target spending.
- Products: the launch of Doritos Protein, which the CEO said has very good consumer momentum.
- Bottling: management is looking at expanding or accelerating refranchising (handing bottling and distribution to partners) in some parts of the country. No decision was announced.
- Break-up question: asked about splitting snacks from beverages, the CEO said only that the company is open to revisiting every option.
The activist investor Elliott Management has held a stake of about $4 billion since 2025, according to reports at the time, and has been pushing for change. Elliott was not mentioned on the earnings call.
What it means for dividend investors
The dividend is $1.48 per quarter, or $5.92 a year, which is about 4.6% at the post-earnings share price of $128.34. The shares traded close to their 52-week low of about $123.47 this week, and about 27% below the 52-week high of $171.48.
Using the $8.14 of core EPS for 2025 cited in our preview, the new guidance implies 2026 core EPS of roughly $8.34 to $8.42, so the annual dividend would be around 70% to 71% of core earnings. That is my own arithmetic, not a PepsiCo figure. It does not make a future raise certain: the company has to fund a $7.9 billion dividend while profit growth slows, and the report itself says North America margins will stay under pressure. Whether that makes the shares attractive is a decision for you to make with your own research.
For taxes and currency when holding U.S. shares from Europe, see the notes at the end of our preview article.
Sources
- PepsiCo, Q3 2026 prepared management remarks (October 8, 2026)
- PepsiCo Form 8-K, Q3 2026 results (October 8, 2026)
- PepsiCo Q3 2026 earnings call transcript (October 8, 2026)
- Zacks via Yahoo Finance, segment volumes and guidance (October 8, 2026)
- MarketBeat, share price and dividend (October 8, 2026)
- CNN, PepsiCo snack price cuts (February 3, 2026)
- Bloomberg, Elliott stake in PepsiCo (September 2, 2025)
Disclaimer: This article is for informational purposes only and does not constitute investment advice. Figures are taken from the sources above as of October 8-9, 2026; share prices and estimates change frequently, so confirm current numbers with your broker or PepsiCo’s investor relations page. Investing involves risk, including the possible loss of capital, and a dividend is never guaranteed.