Pfizer (NYSE: PFE) reports third-quarter 2026 results on Tuesday, November 3, 2026, before the U.S. market opens, with the webcast and analyst call at 10:00 a.m. Eastern. In August the company raised the midpoint of its 2026 revenue guidance and left its adjusted EPS guidance unchanged, and it flagged a one-off charge of about $0.10 per share that falls in the third quarter. This preview lines up the recent quarters against the same quarters a year earlier, works out what the guidance implies for the second half, and covers analyst consensus, the dividend and what to watch.
The recent quarters, each against the same quarter a year earlier
| Metric | Q3 2025 (vs Q3 2024) | Q4 2025 (vs Q4 2024) | Q1 2026 (vs Q1 2025) | Q2 2026 (vs Q2 2025) |
|---|---|---|---|---|
| Total revenues | $16,654 million (-5.9% from $17,702 million) | $17,557 million (-1.2% from $17,763 million) | $14,451 million (+5.4% from $13,715 million) | $15,034 million (+2.6% from $14,653 million) |
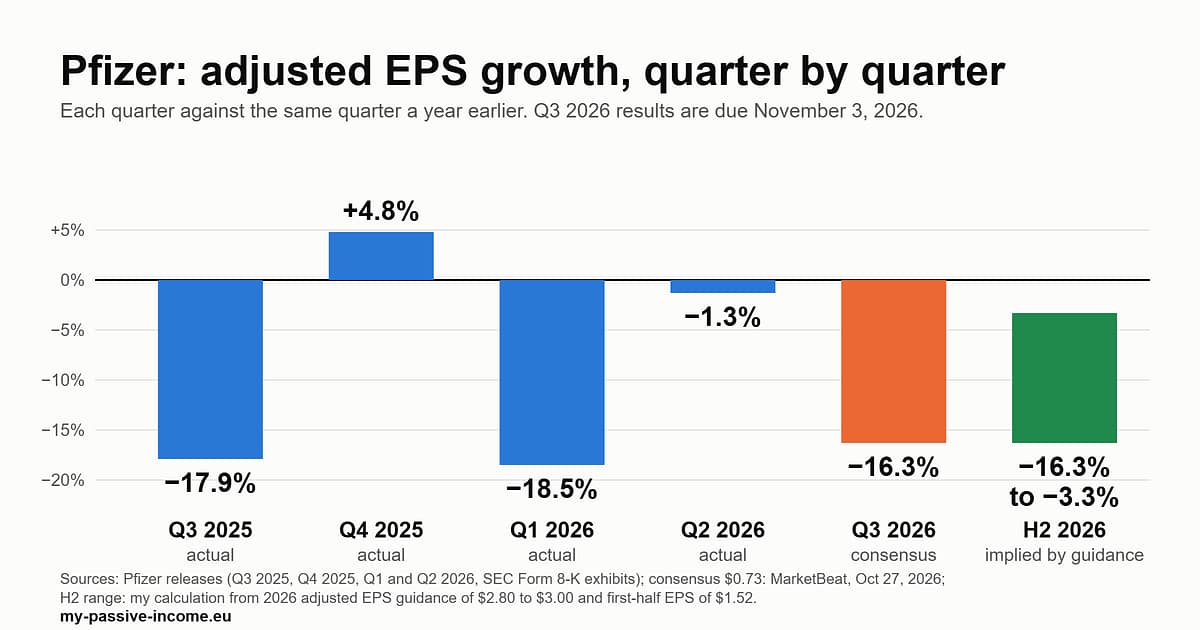
| Adjusted diluted EPS | $0.87 (from $1.06: -17.9%) | $0.66 (from $0.63: +4.8%) | $0.75 (from $0.92: -18.5%) | $0.77 (from $0.78: -1.3%) |
| Eliquis revenues | $2,015 million (from $1,617 million: +24.6%) | $2,020 million (from $1,832 million: +10.3%) | $2,166 million (from $1,923 million: +12.6%) | $2,425 million (from $2,003 million: +21.1%) |
| Vyndaqel family revenues | $1,591 million (from $1,447 million: +10.0%) | $1,688 million (from $1,545 million: +9.3%) | $1,602 million (from $1,486 million: +7.8%) | $1,762 million (from $1,615 million: +9.1%) |
Sources: the four Pfizer earnings releases listed under Sources (Q3 2025 on November 4, 2025; Q4 and full-year 2025 on February 3, 2026; Q1 2026 on May 5, 2026; Q2 2026 on August 4, 2026), as filed with the SEC. The percentage changes are my calculations from the figures in the releases. Adjusted EPS excludes purchase accounting, acquisition costs and other items. Reported (GAAP) diluted EPS was $0.62 in Q3 2025 (from $0.78), a loss of $0.29 in Q4 2025 (from $0.07), $0.47 in Q1 2026 (from $0.52), and a loss of $0.04 in Q2 2026 (from $0.51); the Q2 2026 loss reflected $4.3 billion of non-cash intangible asset impairments. In Q2 2026 Comirnaty revenue was $261 million (from $381 million) and Paxlovid $21 million (from $427 million), while revenue excluding those two products grew 5% operationally.
Full-year guidance: two versions, same EPS range
| Metric (full year 2026) | Initial (December 16, 2025), reaffirmed through May 5, 2026 | Updated August 4, 2026 |
|---|---|---|
| Revenues | $59.5 to $62.5 billion | $60.5 to $62.5 billion (midpoint $61.5 billion, up $500 million) |
| Adjusted diluted EPS | $2.80 to $3.00 | $2.80 to $3.00 (reaffirmed, including about $0.10 for the Innovent charge) |
| Adjusted SI&A expenses | $12.5 to $13.5 billion | $12.5 to $13.5 billion |
| Adjusted R&D expenses | $10.5 to $11.5 billion | $10.5 to $11.5 billion |
| COVID-19 product revenue | about $5 billion | about $4 billion (from about $5 billion) |
Sources: Pfizer’s releases of February 3, May 5 and August 4, 2026. Full-year 2025 revenues were $62,579 million and adjusted EPS $3.22 (company), so the guided ranges equal -3.3% to -0.1% for revenue and -13.0% to -6.8% for adjusted EPS (my calculation). In August the company said non-COVID products should be about $1.5 billion better than previously forecast, that the guidance includes an unfavorable impact of about $1.1 billion from generic and biosimilar competition, and that it assumes about 5.74 billion diluted shares, an effective tax rate of about 15.0% on adjusted income and no share repurchases in 2026. The $650 million acquired in-process R&D charge for the Innovent licensing agreement will be recorded in Q3 2026.
What the guidance implies for the second half (my calculation)
| Item | Revenues | Adjusted EPS |
|---|---|---|
| Second half 2025 (Q3 + Q4, company figures) | $34,211 million | $1.53 ($0.87 + $0.66) |
| First half 2026 (company) | $29,484 million | $1.52 ($0.75 + $0.77) |
| Full-year 2026 guidance (August 4) | $60.5 to $62.5 billion | $2.80 to $3.00 |
| Implied second half 2026 | about $31.0 to $33.0 billion | $1.28 to $1.48 |
| Implied growth, second half 2026 vs second half 2025 | -9.3% to -3.5% | -16.3% to -3.3% |
First-half adjusted EPS was $1.52 against $1.69 in the first half of 2025 (-10%, company). To land inside the guidance, the second half would have to bring in between $1.28 and $1.48, against $1.53 a year earlier, so the guidance range itself allows for a lower second half than a year ago. These are my own calculations from company figures; the company does not publish a second-half forecast, and the Q3 charge of about $0.10 sits inside these numbers.
What analysts expect, and the share price
This section uses third-party data, which is not from the company; each figure carries its source and date. Consensus is for the same quarter, compared with the same quarter a year earlier. The sources differ slightly, so ranges are shown.
| Q3 metric | Consensus for Q3 2026 | Q3 2025 actual (company) | Change |
|---|---|---|---|
| Adjusted EPS | $0.73 (MarketBeat, October 27, 2026: $0.728); $0.72 (Zacks; Barchart, October 16, 2026) | $0.87 | -16.3% to -17.2% |
| Total revenues | $15.86 billion (MarketBeat, October 27); $15.91 billion (Hudson Labs, October 7); $16.13 billion (Zacks, undated article) | $16,654 million | -4.8% to -3.1% |
Two data conflicts: the MarketBeat article lists the year-ago EPS as $0.78 and Hudson Labs lists the year-ago revenue as $16,502 million; Pfizer’s own Q3 2025 release shows adjusted EPS of $0.87 and revenues of $16,654 million, which is what this article uses. For the full year, consensus adjusted EPS is $2.94 (MarketBeat, October 27) to $2.95 (Barchart, October 16), inside the guided $2.80 to $3.00, and Zacks says its 2026 estimate fell from $2.98 to $2.94 over the past 30 days. Hudson Labs shows full-year revenue consensus of $62,278 million (October 7), also inside the guided range. Pfizer beat the EPS consensus in each of the last four quarters (Zacks, Barchart); in Q2 it reported $0.77 against a $0.68 consensus and revenue of $15.03 billion against $14.40 billion (MarketBeat).
If Q3 comes in at $0.72 to $0.73, the implied second half of $1.28 to $1.48 leaves $0.55 to $0.76 for the fourth quarter, against $0.66 in Q4 2025: roughly -17% to +15%, quarter against quarter (my calculation). The width of that range shows how much a Q3 result or a guidance change can move the picture.
MarketBeat reported on October 27, 2026 that PFE opened at $29.80 (an opening price, not a close; 12-month range $23.62 to $30.44; 50-day and 200-day averages $28.30 and $26.67). Its analyst consensus was “Hold” (5 Buy, 14 Hold, 2 Sell among 21 analysts) with an average price target of $28.72. Against the August 4 guidance this gives (my calculation):
| Measure | Value |
|---|---|
| Share price (MarketBeat, October 27, 2026, opening price) | $29.80 |
| Price to 2026 adjusted EPS guidance of $2.80 to $3.00 | about 9.9x to 10.6x |
| Quarterly dividend of $0.43, $1.72 a year | yield about 5.8% on the price above |
| Annual dividend as a share of guided adjusted EPS | about 57% to 61% |
Price and consensus move daily, so check both with your broker before the release. MarketBeat shows a payout ratio of 226%, which is calculated on reported (GAAP) earnings, a different basis from the adjusted guidance used here; reported EPS was depressed by the Q2 impairments. In the first half of 2026 Pfizer paid $4.9 billion in cash dividends, or $0.86 per share, and the company does not expect share repurchases this year (company).
What to watch on November 3
- Adjusted EPS against $0.87 a year earlier and against the $0.72 to $0.73 consensus. The Innovent charge of about $0.10 falls in this quarter, according to the company; consensus asks for a decline of roughly 16% to 17%.
- Any change to full-year guidance. Revenue guidance was raised at the midpoint in August to $60.5 to $62.5 billion while the EPS range of $2.80 to $3.00 was left alone; a Q3 print inside the range implied above would leave both intact.
- Eliquis and Vyndaqel. Eliquis revenue was $2,425 million in Q2 (+21.1%) and Vyndaqel $1,762 million (+9.1%), against $2,015 million and $1,591 million in Q3 2025. Zacks shows segment consensus of $2.38 billion for Eliquis (quoted as alliance revenues, so its definition may differ from Pfizer’s reported line), $1.68 billion for Vyndaqel, $1.66 billion for Prevnar (Q3 2025: $1,742 million), $776 million for Comirnaty and $326 million for Paxlovid.
- COVID-19 products. Pfizer now expects about $4 billion of COVID-19 product revenue in 2026, down from about $5 billion. Q2 Comirnaty and Paxlovid revenue totalled $282 million against $808 million a year earlier (my calculation from the release).
- Generic and biosimilar competition. The company’s guidance includes an unfavorable impact of about $1.1 billion this year, and Barchart lists upcoming patent expirations among the main risks for the stock.
- Obesity and the pipeline. In its Q2 release the company said it plans to advance 10 Phase 3 studies of berobenatide, a monthly GLP-1 receptor agonist, in 2026; Hudson Labs reports a first approval is targeted for 2028.
- Costs. Barchart and Hudson Labs report that Pfizer has raised its net cost-savings target to $9.7 billion through 2029; the full-year guide for adjusted SI&A is $12.5 to $13.5 billion.
The dividend
On October 6, 2026, Pfizer declared a fourth-quarter dividend of $0.43 per share ($1.72 a year), the same as the previous quarter. It will be the 352nd consecutive quarterly dividend. The record date is November 6, 2026 and it is payable on December 7, 2026 (Pfizer press release, as reprinted by BioSpace). MarketBeat lists November 6 as the ex-dividend date too; under the current one-day settlement cycle that normally means shares bought up to the close of November 5 receive this payment, but confirm the date with your broker. The previous dividend, the 351st, had a record date of July 24 and was paid on September 1, 2026.
For investors in Europe
- PFE pays in U.S. dollars, and U.S. withholding tax applies by default; the rate for non-U.S. investors depends on your broker having a valid Form W-8BEN. See our W-8BEN guide.
- The dollar and euro exchange rate moves the euro value of the dividend independently of anything Pfizer reports.
Sources
- Pfizer: invitation to the November 3, 2026 results webcast and call
- Pfizer: Q3 2025 results, Form 8-K exhibit (November 4, 2025)
- Pfizer: Q4 and full-year 2025 results, Form 8-K exhibit (February 3, 2026)
- Pfizer: Q1 2026 results, Form 8-K exhibit (May 5, 2026)
- Pfizer: Q2 2026 results and 2026 guidance, Form 8-K exhibit (August 4, 2026)
- Pfizer: third-quarter 2026 dividend declaration (June 2026)
- Pfizer: fourth-quarter 2026 dividend declaration (October 6, 2026, reprinted by BioSpace)
- Third-party data (consensus, price and commentary), not from the company: MarketBeat (October 27, 2026); MarketBeat earnings page (consensus for November 3); Zacks Equity Research via TradingView (undated); Barchart via Webull (October 16, 2026); Hudson Labs (October 7, 2026)
Get new articles by email
Ex-dividend dates, earnings previews and P2P platform changes, straight to your inbox. Unsubscribe anytime.
Disclaimer: This article is for informational purposes only and does not constitute investment advice. Company figures are taken from the releases listed; consensus and the share price come from the third-party sources listed, as of the dates stated; and the second-half, fourth-quarter and valuation figures are my own arithmetic, not a company forecast. Confirm current figures with your broker or the company’s investor relations page. Investing involves risk, including the possible loss of capital, and a dividend payment is never guaranteed.