Philip Morris International (NYSE: PM) reported third-quarter 2026 results on October 21, 2026, before the U.S. market opened. Adjusted earnings per share came in at $2.36, above both the company’s own guidance and analyst consensus, and the full-year forecast was nudged up. Below: the numbers against what we flagged in our preview, the outlook, how the valuation multiples moved, and what is still a question mark.
The quarter in numbers
| Metric | Q3 2026 | Change vs Q3 2025 |
|---|---|---|
| Net revenues | $11,438 million | +5.5% reported, +7.1% organic |
| Adjusted diluted EPS | $2.36 | +5.4% reported, +5.8% excluding currency (currency effect: $0.01) |
| Reported diluted EPS | $2.12 | -4.9% (Q3 2025: $2.23) |
| Adjusted operating income | $5,117 million | +9.6% reported, +10.5% organic |
| Heated tobacco unit shipments (IQOS) | 41.5 billion units | +1.5% |
| ZYN shipments in the U.S. | 3.2 billion pouches | +4.2% |
| U.S. oral smoke-free segment | 3.7 billion units in Q3 (+2.3%) | 10.0 billion units year to date (-5.8%) |
| Smoke-free share of net revenues | more than 40% in Q3 | about 42% year to date |
Source: Philip Morris International third-quarter 2026 release (Business Wire, October 21, 2026, 6:59 a.m. Eastern). The release excerpt I reviewed does not state the reason for the drop in reported EPS, so I do not offer one; check the full release if it matters for your decision.
Against guidance and consensus
| Item | Expected | Actual | Difference |
|---|---|---|---|
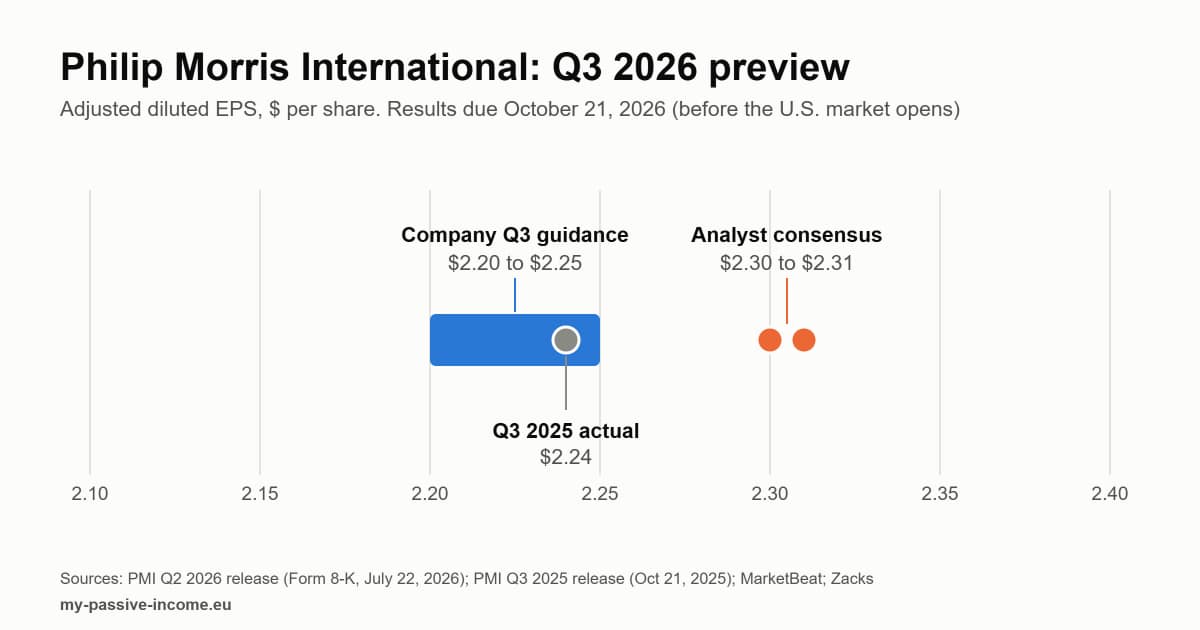
| Adjusted EPS vs company guidance (July 22, 2026) | $2.20 to $2.25 | $2.36 | $0.11 above the top of the range |
| Adjusted EPS vs consensus (MarketBeat / Zacks, October 2026) | $2.30 / $2.31 | $2.36 | $0.06 / $0.05 above |
| Net revenues vs consensus (MarketBeat / Zacks) | $11.32 billion / $11.42 billion | $11.438 billion | about 1.0% / 0.2% above |
| Currency effect on Q3 EPS | $0.08 unfavorable (July estimate) | $0.01 unfavorable | much smaller than guided |
In the preview we noted that consensus sat above the company’s own range. That gap turned out to be justified: the company’s July range was beaten comfortably, and a currency headwind far smaller than the 8 cents it had estimated explains part of it.
Outlook: raised, but with caveats
- Full-year adjusted EPS: $8.29 to $8.44 (up 9.9% to 11.9%), versus $8.26 to $8.41 in July. Excluding currency the range is unchanged at $8.11 to $8.26 (up 7.5% to 9.5%).
- Reported diluted EPS forecast: $7.11 to $7.26.
- Organic revenue growth: 5% to 7%, with the middle or upper half more likely.
- Organic operating income growth: 7% to 9%, with the middle or lower half more likely.
- Fourth quarter: the company expects international smoke-free to reaccelerate, plans to increase U.S. ZYN investment, and expects energy-related input price increases to weigh slightly more.
- Cash and balance sheet: operating cash flow of about $13.5 billion, no share buybacks planned in 2026, and a net debt to adjusted EBITDA target of close to 2.0x by year end.
Two soft spots are visible in the numbers: heated tobacco shipments grew only 1.5% in the quarter, and the U.S. oral segment is still down 5.8% year to date despite the Q3 uptick.
The share price and the multiples
GuruFocus reported at 8:56 a.m. Eastern that PM shares were down about 3.5% in pre-market trading, around $199.90, citing declining organic sales in the U.S. and rising input costs. That is a pre-market price, not a closing price, and it will have moved by the time you read this. Using it, and the dividend and guidance figures, the multiples compare as follows (my calculations):
| Measure | Before results (price $204.54, Oct 16) | After results (price about $199.90, pre-market Oct 21) |
|---|---|---|
| Forward P/E on the midpoint of full-year adjusted EPS guidance | 24.5x (midpoint $8.335) | 23.9x (midpoint $8.365) |
| Dividend yield on $6.40 a year | 3.13% | 3.20% |
| Annual dividend as a share of guidance midpoint | 76.8% | 76.5% |
Prices: 24/7 Wall St. (October 16, 2026) and GuruFocus (October 21, 2026, pre-market). Dividend: quarterly $1.60, $6.40 annualized (company, September 2026). Valuation sites that show a higher trailing P/E or payout ratio use reported rather than adjusted earnings.
For investors in Europe
- The $1.60 quarterly dividend (up 8.8% in September) is payable on October 26, 2026. The ex-dividend date was October 2, so buying now does not earn this payment.
- PM pays in dollars and U.S. withholding tax applies by default; the rate for non-U.S. investors depends on your broker having a valid Form W-8BEN. See our W-8BEN guide.
- A stronger dollar helps the euro value of the dividend but, as this quarter and the guidance both show, it also moves PM’s reported earnings.
Sources
- Philip Morris International: 2026 third-quarter and first nine-months results (Business Wire via FinancialContent, October 21, 2026)
- Philip Morris International: Q2 2026 results, Form 8-K exhibit (July 22, 2026)
- Philip Morris International: Q3 2025 results, Form 8-K exhibit (October 21, 2025)
- Philip Morris International: September 2026 dividend announcement, Form 8-K
- GuruFocus: PM posts strong Q3 results but shares slip (October 21, 2026, 8:56 a.m. Eastern)
- MarketBeat: PM Q3 2026 earnings date and estimates
- Zacks via TradingView: Philip Morris Q3 earnings on deck
- 24/7 Wall St.: Philip Morris just raised its dividend 8.8% (October 16, 2026)
Disclaimer: This article is for informational purposes only and does not constitute investment advice. Figures are taken from the company release and the third-party sources listed; share prices change continuously and the prices used here are time-stamped as stated. Confirm current figures with your broker or the company’s investor relations page. Investing involves risk, including the possible loss of capital, and a dividend payment is never guaranteed.